
P2P lending (crowdlending) is one of the highest-yielding – and riskiest – asset classes available to retail investors. In Europe alone, there are more than 200 platforms on which you can invest in loans. This guide explains how P2P lending works, which risks you need to know, how the buyback guarantee really works and how your returns are taxed.
All of the following information is based on my own experience as a P2P investor since 2017. Please note that none of this constitutes investment advice. More on that in the disclaimer.
Which P2P Platform Is Right for You?
This guide explains how P2P lending works and what you need to pay attention to. For the platform choice itself, I maintain dedicated, continuously updated overviews: all providers I have tested can be found in the P2P platform reviews, the safety ranking in the re:think P2P Risk Score, and the financial stability of the loan originators in the P2P Loan Originator Comparison. Current sign-up offers are listed on the bonus page.
And if you want to know right away which providers currently perform best: the ranking of the safest P2P lending platforms 2026 summarises the top 5 at this point in time.
What Is P2P Lending?
The acronym P2P stands for “peer-to-peer”, meaning “from person to person”. P2P loans are therefore loans granted by private individuals to other private individuals.
Characteristic of this type of lending is the complete, or at least extensive, bypassing of traditional banks and credit institutions. Instead, lenders and borrowers meet on online marketplaces, also known as P2P platforms.
Most P2P loans are consumer loans in the three-digit or low four-digit range. However, business, real estate and even agricultural loans have since become part of the spectrum as well.
In a financial context, this investment segment falls under the umbrella category of crowdfinance. This term covers all activities and offerings connected to the financing and involvement of many individuals.
Crowdfinance can in turn be roughly divided into three categories: crowdfunding, crowdinvesting and crowdlending. Classic P2P consumer loans are assigned to the last of these.
2005: The First P2P Lending Providers
Since P2P loans are brokered online, the emergence and spread of this asset class only became possible through the technical development of the internet.
The world’s first P2P lending provider was the British company Zopa, which launched its service on 1 March 2005. The vision of its five founders was to create a technology that could serve as a link in loan brokerage between borrowers and lenders, without having to rely on a bank.
The United States also has a long and established history in brokering loans between private individuals. The first US provider of private loan brokerage was the P2P platform Prosper Marketplace, which, like Zopa, was founded in 2005.
The platform that was at times the largest P2P platform in the world also came from the USA: Lending Club, founded in 2006. The platform is also well known because it became the first and so far only company from the P2P lending space to go public, recording the largest IPO of a technology company in the USA in 2014. At the end of 2020, however, Lending Club withdrew completely from the retail P2P business and has operated as a licensed bank ever since.
How Do P2P Platforms Work?
P2P platforms are digital intermediaries from the fintech sector that bring together loan supply and investor demand.
This means the platforms always have to work in two directions: on one side, funds have to be acquired from investors, which ultimately finance the loans. To be as attractive as possible to investors, many companies advertise high return promises, bonus campaigns or safeguards against payment defaults.
On the other side, P2P lending platforms take care of providing a sufficient loan supply. The loan originators can either be directly affiliated with the P2P provider (classic P2P lending) or be external loan originators with no overlap with the platform (P2P marketplace model). Depending on the business model, the P2P platform either handles the acquisition of new borrowers itself or monitors the portfolio quality of external loan originators.
In the end, both the investors’ money and the loan supply are brought together on the P2P platform.
What Returns Can Be Achieved?
The returns that can be achieved with P2P lending can vary considerably, as they depend on several factors.
- Interest rate: One of the most important factors is the interest rate itself. It differs from platform to platform and can depend, among other things, on investor demand or on the market conditions of the respective loan originator. The collateralisation of the loans can also influence the level of the interest rate.
- Bonus: The greater the need for capital, the more frequently P2P lending platforms market bonus campaigns, which can push the overall return expectation. New investors are also typically offered bonus payments or cashback campaigns when they sign up to a platform.
- Performance: Beyond the interest rate, the performance of the loan portfolio is the biggest factor influencing the overall return. The more loans default and cannot be recovered, the stronger the impact on the achievable return.
I have personally been investing in P2P lending since 2017. Here is an insight into the annual returns I was able to achieve in 2025 across the different platforms in my portfolio.
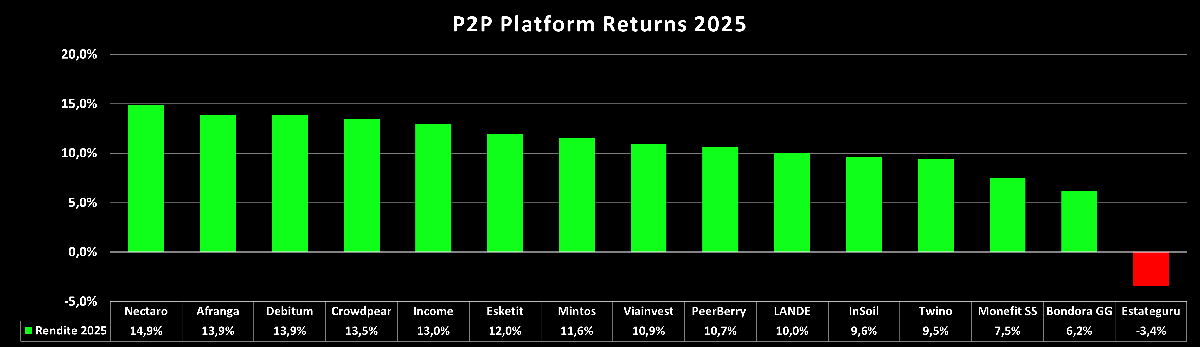
As the chart shows, I achieved a positive annual result on 14 out of 15 platforms, with double-digit returns on ten of them.
Advantages and Disadvantages of P2P Lending
Investing in P2P lending comes with certain advantages as well as disadvantages. Some of them are listed below.
The Advantages
- Low entry barrier: Anyone can open an account within a few minutes and start investing.
- Regular cash flow: P2P lending offers income-oriented investors a reliable way to regularly draw capital gains from their investments.
- Automated investing: Most P2P lending platforms offer automated systems through which the money can be reinvested automatically.
- Portfolio diversification: Alongside asset classes such as real estate, stocks, funds or commodities, P2P lending offers an additional option to diversify an investment portfolio.
- High liquidity: P2P lending offers flexibility and short-term access to your funds. Either via short-term consumer loans, the use of a secondary market or special investment products with high liquidity.
The Disadvantages
- High-risk investment: Many P2P lending platforms are based abroad and are insufficiently controlled and supervised, which is why there have been several scams and fraud attempts in the past. But even with supposedly “safe” platforms, poor risk management can lead to losses for investors.
- Leveraged loans: At their core, P2P loans are investments in already pre-financed loans. While this leverage can generate a profitable return on equity for loan originators, poor portfolio quality and insufficient liquidity can also result in insolvency.
- Active investment: Automated investing is certainly an advantage of P2P lending, but it does not make the asset class a passive investment. Because P2P platforms operate in a dynamic environment in which the risk profile can change very quickly, a certain degree of activity is required with P2P investments.
How Do I Start Investing in P2P Lending?
The entry barrier for P2P lending investments is very low. To make sure the start does not come with expensive lessons, I recommend the following five steps:
- Define your risk budget: Only invest money whose total loss you could cope with in the worst case. In most cases, P2P lending is used as an addition to a portfolio, not as its foundation.
- Choose platform and loan originators: Get an overview before following the first advertisement you see. The detailed platform reviews and the loan originator comparison provide a quick entry point.
- Open an account: Registration and identity verification usually take only a few minutes. Many platforms offer new investors a bonus or cashback. A nice head start, but not a selection criterion.
- Start conservatively: Begin with small amounts per loan and deliberately limit maturities and loan originators. Don’t give in to FOMO and expand your investment only as your experience grows.
- Monitor actively: P2P lending is a dynamic and by no means passive asset class. Stay informed and, for example, follow my news page regularly so you can react quickly if needed.
Risks of P2P Lending Investments
There is a wide range of risks that can arise in the context of a P2P lending investment. These either affect the P2P lending platforms directly (platform risk) or their loan originators (loan originator risk).
On both levels, there are economic risks as well as the associated market risks of the lending business. These include risk factors such as country risk, interest rate risk, liquidity risk or currency risk.
Default Risk
The achievable return on a P2P platform is largely determined by the performance of the loan portfolio. The default risk of loans therefore plays an important role in the assessment of a platform. A default occurs when the borrower exceeds a certain period of time, usually 60 or 90 days, during which no repayments have been made in accordance with the repayment schedule.
However, a loan default does not mean that the money is automatically lost. Through the debt collection process carried out after the default, all or part of the outstanding claims can well be recovered.
No universal statement can be made about the level of default rates at individual P2P platforms. The decisive factor here is the transparency of the respective company and how openly it communicates the performance of the loan portfolio. Investors should therefore closely observe and question which information a platform publishes – or does not publish – about the default risk of its loans.
Misjudged Creditworthiness
Most loan originators have a systematic assessment process for evaluating the creditworthiness of borrowers. Depending on the loan segment, there can be significant differences. The creditworthiness of a private individual who wants to take out a short-term, unsecured consumer loan of up to 1,000 euros usually differs considerably from an agricultural business that wants to purchase new machinery for 100,000 euros.
How well or poorly a loan originator has done its homework in assessing creditworthiness can be seen, for example, in the NPLs (non-performing loans), which are usually published in the annual financial statements. These are distressed loans that are very unlikely to be recovered and therefore have to be written off.
What Happens in the Event of a Payment Default?
If a payment default occurs, the P2P lending platforms try to recover the money through a debt collection process. Since there are different types of loans, the security and recovery mechanisms vary considerably.
With consumer loans, many loan originators are liable to investors in the form of a buyback guarantee, under which loan defaults are repaid out of their own pocket. The prerequisite for this is their economic condition.
With mortgage-secured loans, such as real estate, the proceeds from the sale of the collateral determine how much money investors will ultimately get back.
With other platforms, there is no protection at all, which is why investors have to bear the default risk directly. With such providers, it is all the more important to hold the broadest possible portfolio of loans.
Insolvency or Closure of the P2P Marketplace
Another risk with P2P lending is insolvency, i.e. the inability of a platform to pay. Most P2P marketplaces are essentially asset managers that receive a commission for their brokerage activities depending on the loans financed.
Investors should therefore familiarise themselves with the business models of the individual P2P lending providers and their financial situation. Audited annual financial statements, where published, provide valuable insights here.
The Buyback Guarantee in P2P Lending
A few years ago, Mintos established the so-called buyback guarantee (also buyback obligation) on its P2P marketplace. This concept, designed to eliminate the supposed default risk for investors, was subsequently adopted by many P2P providers. Today it is one of the key safety features of loan originators financing unsecured consumer loans.
How It Works
The mechanics of the buyback guarantee are relatively simple: As soon as a loan is overdue for a certain period, the issuer (the loan originator) commits to buying back the claim from the investor. As a rule, this period is 60 days. At individual P2P lending platforms, however, the buyback obligation period is 30 or 90 days.
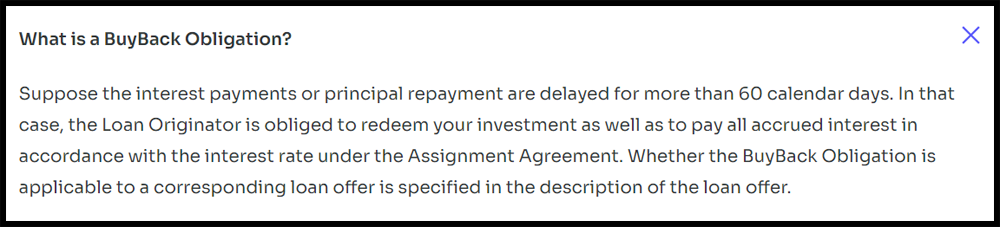
In addition to the outstanding principal, the accrued interest is usually also reimbursed.
Which Platforms Offer a Buyback Guarantee?
The buyback guarantee can be found at many P2P lending platforms where loan originators offer unsecured consumer loans. These include loan originators on Mintos, Nectaro, PeerBerry or Income Marketplace. P2P platforms that offer collateral for their loans (mortgages, land, machinery, etc.) generally do not have any form of buyback guarantee.
When Does the Buyback Guarantee Kick In?
The timing of the buyback obligation differs considerably from one P2P lending provider to another. At Swaper or Robocash, the buyback takes place after just 30 days of payment delay. At Mintos, PeerBerry, Esketit or Income Marketplace, it is 60 days. The longest buyback period is at Debitum with 90 days.
Advantages and Disadvantages of the Buyback Guarantee
The big advantage of the buyback guarantee is that the supposed default risk of the loan is eliminated. As long as the buyback guarantee is being honoured, this offers investors reliable repayments and a predictable cash flow.
The disadvantage of the buyback guarantee is that investors may be blinded by a “false sense of security” as it is ultimately only as reliable as the payment behaviour of the issuer. Should the issuer run into financial problems, the shifted default risk will fall back onto the investor.
Regulation of P2P Platforms
For a long time, P2P lending was considered a largely unregulated grey market. That has changed: a large share of European platforms now holds a licence and is subject to state supervision. However, the level of regulation differs considerably from platform to platform.
In practice, four tiers can be distinguished:
- MiFID II (investment firm): The most comprehensive form of regulation. Licensed investment firms are subject to strict compliance requirements and additionally offer an investor compensation scheme that covers up to 20,000 euros per investor in the event of insolvency or misappropriation.
- ECSP (EU crowdfunding licence): The European Crowdfunding Regulation enforces, among other things, regulatory requirements to avoid conflicts of interest between the platform operator and the loan projects. There is no investor compensation scheme here.
- EMI (electronic money institution): Also supervised, but with a focus on payment services rather than investment products.
- SRO (self-regulation): The weakest form of oversight. The platform voluntarily submits to the standards of a self-regulatory organisation, for example regarding anti-money-laundering and due diligence. However, this does not involve any state supervision of the investment business.
In addition, some platforms continue to operate entirely without a licence. That does not automatically make them dubious, but investors lack the institutional protection framework in the event of a crisis.
What matters is understanding what regulation can and cannot deliver. It enforces minimum standards for capital resources, compliance and transparency and creates a legal framework for the worst case. However, it protects neither against loan defaults nor against poor risk management. The investor compensation scheme is not a deposit guarantee either: it applies in the event of misappropriation or insolvency of the intermediary, but not to defaulted loans.
How each individual platform is regulated feeds into the re:think P2P Risk Score as a dedicated category.
How Is P2P Lending Income Taxed?
Interest earned through P2P lending constitutes taxable income in virtually every country. How much you pay depends on your tax residency. Unlike a bank or broker, P2P platforms generally do not withhold taxes at source: declaring this income is your responsibility.
Most platforms provide an annual tax report summarising your interest income. When in doubt, consult a tax advisor familiar with the treatment of foreign investment income in your country.
Depending on the platform’s country of residence, a local withholding tax may additionally be deducted from your interest income. In many cases, it can be reduced or credited against your domestic tax liability by submitting a certificate of tax residency.
P2P Lending Guide FAQ
P2P loans are loans financed by retail investors via online platforms without a bank as an intermediary. In return, investors receive interest, but also bear the default risk of the loans and the risk of the platform itself.
No. P2P lending is a high-risk asset class in which a total loss is possible in the worst case scenario. However, the risks differ considerably from platform to platform. The re:think P2P Risk Score offers a systematic comparison based on five categories.
It varies. Many European platforms now hold a licence, for example as an investment firm (MiFID II) or under the EU Crowdfunding Regulation (ECSP). However, big platforms continue to operate unregulated. Regulation enforces minimum standards, but does not protect against loan defaults.
Interest rates vary considerably depending on the platform and typically range between 8% and 14%. In my experience, after deducting possible defaults, a realistic net return expectation lies between 6% and 10%.
Only as much as you could cope with losing entirely. For most retail investors, P2P lending is an addition of a few percent of the overall portfolio, spread across several platforms and loan originators rather than concentrated on a single provider.
Interest from P2P lending is taxable income in virtually every country. The amount depends on your tax residency. Since the platforms generally do not withhold taxes at source, you have to declare this income yourself. Most platforms provide an annual tax report for this purpose.
There is no deposit guarantee scheme. While the loan claims legally continue to exist, the wind-down is lengthy in practice and the outcome uncertain. At MiFID II-regulated platforms, an investor compensation scheme of up to 20,000 euros applies in the event of insolvency or misappropriation. However, even this does not cover loan defaults.
On this blog you will find detailed platform reviews of individual P2P platforms, continuously updated comparisons and scores, as well as news from the P2P market several times a week.