
New investors receive a tiered Bonus with the code INVEST26. €25 from €1,500, €35 from €2,500, €75 from €5,000, €175 from €10,000 and €500 from €25,000. Qualifying products: Loans, Bonds, ETFs, Real Estate and Crypto-ETPs (Mintos Smart Cash excluded). I am invested with my own funds at Mintos since July 2024. Since then, I achieved a total return (XIRR) of 12,25%. My outstanding portfolio on the platform stands at 17.000 €. Mintos is a P2P marketplace based in Latvia, which is operated by AS Mintos Marketplace. The operational launch of the platform took place in 2015. In the following years, Mintos has developed into one of the largest P2P platforms in Europe, thanks to a highly scalable business model with externally connected lenders. Mintos currently manages investor assets of EUR 600+ million, with more than 500,000 registered users. With its licence as a European investment company, Mintos has increasingly integrated other asset classes on the platform. In addition to the traditional and historically grown range of loans, the platform’s portfolio now also includes ETFs, bonds and real estate. All key facts and figures about Mintos at a glance. With his experience in the financial sector (Ernst & Young, later investment banker at SEA) and his natural interest in technology, he wanted to combine both of his passions. After reading an article about the British platform Landbay on TechCrunch, he became aware of the P2P lending business model. Together with Martins Valters, who had previously been his supervisor at Ernst & Young, the two founded the company Mintos in 2014. How does Mintos make money? The P2P marketplace generated revenue of EUR 14.1 million last year, spread across nine different income sources. Mintos earned 73.4% of its revenue (EUR 10.4 million) from service fees. These are fees charged to lending companies for listing assets on the Mintos platform. Historically, this position has always been the largest source of revenue for Mintos. Net interest income, amounting to EUR 1.1 million (8.1% of revenue), was generated from uninvested investor funds. For context: Since receiving its investment brokerage license in 2021, Mintos has maintained a business relationship with the asset manager BlackRock, through which the platform parks uninvested investor funds in a money market fund managed by BlackRock. Other revenue sources include bond placement fees, management fees, one-off transaction fees charged to lending companies, inactivity fees for investors, commissions on foreign exchange conversions, and fees from transactions on the secondary market. These smaller items together account for approximately 18.5% of Mintos’ total revenue. Over the years, there have been several in-person meetings with Mintos founder and CEO Martins Sulte: In March 2019 in Riga, in late 2020 in Berlin and most recently in June 2024 also in Riga, as part of my P2P Lending Trip through the Baltic States. Already back in 2019, Martins has left a positive impression on me. Open, engaged and notably more approachable than expected. The most recent conversation in 2024 covered topics including the transformation of Mintos into a multi-asset platform, the development of the loan market and the launch of Mintos Smart Cash. Those interested in the content of our more recent conversations, here are the recorded interviews: December 2020 | January 2021 | June 2024 P2P lending is a dynamic asset class where investors should stay continuously informed. You will find the latest news on Mintos on my P2P lending news page, where I cover other P2P platforms as well. Mintos has launched a new bonus campaign for new investors. From August 24 to September 30, investors can receive a bonus of up to €500 by using the code INVEST26, depending on the amount invested. The bonus tiers start at an investment of €1,500, which qualifies for a €25 bonus. This is followed by €35 (from €2,500), €75 (from €5,000), and €175 (from €10,000). The maximum bonus of €500 is only available for investments of €25,000 or more. Investments in loans, bonds, ETFs, real estate, and crypto ETPs are eligible, while Mintos Smart Cash is excluded. Investors can now buy individual ETFs on Mintos instead of being limited to the pre-built Core ETF portfolios. The platform now offers access to more than 1,000 UCITS ETFs from providers such as iShares, Vanguard, and VanEck, with a minimum investment of just EUR 1. According to Mintos, there are no trading or custody fees for ETF investments. Instead, investors only pay the ETF's ongoing costs, known as the Total Expense Ratio (TER). Mintos states that these fees average below 0.1%. Another important point: Just like the platform's other investment products, the ETF portfolio is covered by the investor compensation scheme of up to EUR 20,000. As previously covered, interest payments on Nera Capital loans have been suspended since March 26. The reason behind this is the ongoing solvency reviews conducted by the UK’s Solicitors Regulation Authority (SRA) concerning the law firms that Nera Capital works with. Mintos has now communicated that the scheduled principal repayments due on May 20 were not made, and that further repayment delays are expected. It was also clarified that the SRA review is focused on a specific group of UK law firms handling high case volumes, not the entire litigation finance sector, as originally communicated by Nera Capital. According to Mintos, active negotiations are currently underway with Nera Capital, the law firms, and other financiers to protect the ongoing legal cases. A restructuring of the loan terms is therefore a realistic possibility. However, a full resolution is not expected in the short term, as the resumption of payments will depend heavily on the completion of the SRA review. More than EUR 60 million of investor funds are affected. Alternatively, you can subscribe to my Telegram channel or WhatsApp group (both free of charge) to receive real-time updates as soon as new developments emerge. Who are the main shareholders and management executives behind Mintos? Let’s have a look! Who owns Mintos? The Latvia based P2P platform is operated by the company “AS Mintos Marketplace”. This company in turn belongs to the parent company “AS Mintos Holdings”. If we take a look in the Latvian company register, we will find a large number of different shareholders for this company. The largest share, 30.52%, belongs to AS ALPPES Capital, which is 100% controlled by Aigars Kesenfelds. The Latvian multimillionaire, who was one of the four founders of 4finance in 2008, rarely appears in public. However, his reputation precedes him by far. The article “The Fast Millionaire” portrays the rise and background of Aigars Kensenfelds’ empire and also reveals his links to Mintos. Mintos is represented at the top of the management team by CEO and co-founder Martins Sulte. The Latvian citizen worked as an investment banker at SEB for six years after studying economics at the University of Riga. After receiving his MBA in 2013, he then founded the Latvian P2P marketplace with Martins Valters, his former supervisor at Ernst & Young and current COO at Mintos. In personal meetings with Martins from 2019 to 2024, he always made a tidy and competent impression. He was also frequently available to answer questions outside of official interviews. In order to invest on Mintos, investors must meet two important requirements: A minimum age of 18 years and proof of a European bank account in their own name. The registration process on Mintos is very simple and intuitive. After opening an account via email, the KYC and AML questionnaires must be filled out. This is followed by the verification of identity and the declaration of tax residence.
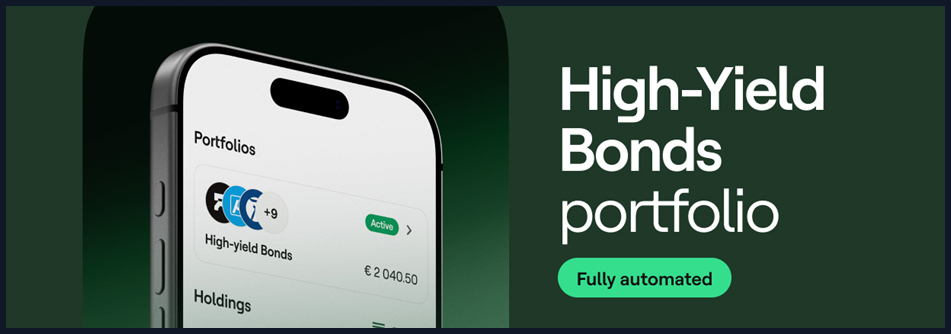
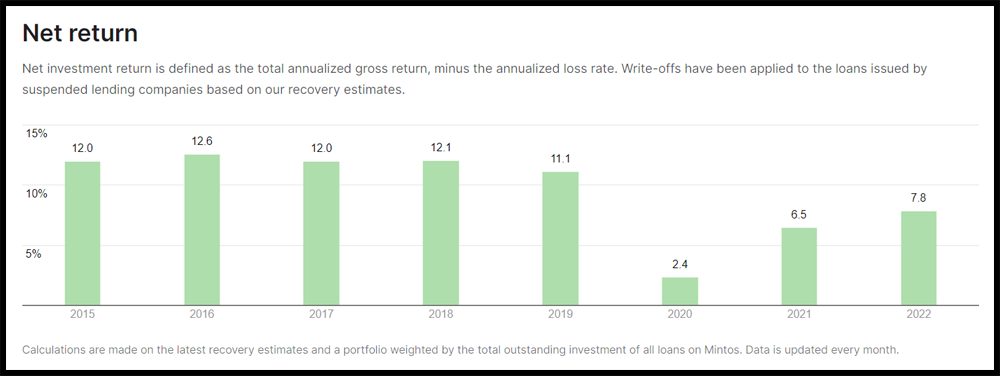
New investors receive a tiered Bonus with the code INVEST26. €25 from €1,500, €35 from €2,500, €75 from €5,000, €175 from €10,000 and €500 from €25,000. Qualifying products: Loans, Bonds, ETFs, Real Estate and Crypto-ETPs (Mintos Smart Cash excluded). A cross-platform overview with all bonus offers and cashback promotions can be found by investors on the bonus page. How does Mintos work and what should investors know and consider when investing on the marketplace? In the following sections of my Mintos review you will find all the necessary information that you need. The 80+ lenders represented on Mintos offer a variety of different loan types. These include: From an investor’s perspective, the large number of loan types is a big advantage in terms of diversifying the loan portfolio on Mintos. Investors can achieve further diversification with the geographical selection of their P2P loans, as up to 33 different countries can be selected for investments. The geographical focus is on Europe, with a focus on the Baltic States, the Balkans and Eastern Europe. However, it is also possible to invest in Africa (South Africa, Zambia, Namibia, Botswana, Kenya), South America (Colombia, Mexico) or South East Asia (Philippines, Vietnam, Indonesia). The terms of the loans depend on the lending company and the structure of the individual bonds (notes). Due to its licensing as a brokerage company, Mintos can make further asset classes accessible to its investor community, apart from the lending business. Since October 2023, this also includes the possibility to invest in bonds. Interesting here is both the low minimum investment amount of only EUR 50 and the fact that there are no management fees. The first offer on Mintos comes from Eleving Group (formerly Mogo). The bond of EUR 3 million runs for 5 years and offers investors an interest rate of 13%. In November 2025, Mintos launched the automated “High-Yield Bonds Portfolio,” an expansion of its existing bond offerings. The idea is fairly simple: instead of selecting individual bonds, Mintos creates a broad portfolio with at least 20 different high-yield bonds from various industries. Advantages for investors: broader diversification, more predictable and regular income, and a daily cash-out feature (liquidity depending on market conditions). The minimum investment amount is set at EUR 50. Until the end of 2025, the bond portfolios will be free of charge. Starting in 2026, an annual management fee of 0.39% will apply. The introduction of the “High-Yield Bonds Portfolio” strongly resembles Mintos’ launch of Invest & Access in 2019, which aimed to offer an alternative to Bondora Go & Grow. At least the three underlying goals are nearly identical: increase revenue, integrate less popular offerings, and provide seemingly more liquidity for investors. With the Mintos Core ETF portfolio, the P2P marketplace added another asset class in December 2023. The platform takes care of all portfolio management aspects, including market analysis, selecting ETFs and scheduling transactions. Based on a catalogue of questions, the company puts together an ETF portfolio that is designed to meet the investor’s risk tolerance and investment objectives. Investments in the Mintos Core ETF can be made from as little as EUR 50. Mintos does currently not charge any fees for this service. In June 2024, the P2P marketplace launched Mintos Smart Cash. Here, investors can invest their cash reserves flexibly and achieve a return of up to 2.0%. The return is generated by a money market fund which is managed by BlackRock. Mintos has been working with BlackRock since its IBF licensing and manages non-invested funds from its investor accounts there. This enabled Mintos to generate a revenue of EUR 1.2 million in 2023 (10.7% of total revenue). Further details of Mintos Smart Cash have been discussed with CEO Martins Sulte during my stay in Riga. Since March 2026, investors on Mintos can also invest in cryptocurrencies. This is done via regulated crypto-ETPs, meaning no wallets, private keys, or external exchanges are required. Mintos therefore provides a simple and regulated way to access traditional crypto investments. At the launch, seven cryptocurrencies are available (Bitcoin, Ethereum, Ripple, Solana, TRON, Avalanche, and Litecoin), which can be traded via well-known product providers such as BlackRock iShares and VanEck. The crypto-ETPs (Exchange Traded Products) are traded on regulated European markets and are physically backed. This means the underlying cryptocurrencies are actually held, reducing risk compared to synthetic products. Crypto trading on Mintos is possible from as little as EUR 5, with transaction fees of 0.49% (or a minimum of EUR 0.99). Trading remains free of charge until the end of April 2026. Investors can register on Mintos free of charge. There are also no costs or hidden fees for deposits and withdrawals. However, there are some cost factors on Mintos to consider. According to Mintos, the net return on the platform is between 10% and 12%. The calculation is made including an annual loss ratio. For this reason, the return on investment in 2020 is only at 2.4%. Write-downs were taken on loans issued by suspended credit entities based on our recovery estimates. Afer being five years with Mintos, my personal return is at 10.79%. However, there are still more than EUR 1,000 in the recovery process, which I declared as a loss since no recoveries have been made for two straight years. As a result, my total return has dropped to 7.22%. Mintos offers an Auto Invest feature (Mintos Custom Loans), which allows users to set individual criteria for loan selection in advance. This means that loan repayments are automatically reinvested, eliminating the need for manual handling. With Mintos Auto Invest, the following settings, among others, can be configured: The minimum investment amount on Mintos is EUR 10. Since May 16, 2025, an annual fee of 0.29% is charged for using the “Custom Loan Portfolios.” This fee applies to both the primary and the secondary market. Mintos launched a smartphone app for its investors in February 2020. Check here for iOS (App Store) and Android (Play Store) to download the app. After Mintos has become a licensed brokerage company, the platform is now legally obligated to withhold taxes on your income earnings that derives from investments into regulated financial instruments (Notes). The tax will be automatically withhold after receiving an interest payment. The applicable tax rate is depending on the country of your tax residency and according to the submitted tax information and certificates. Mintos faced several crises and problems in the past. While the origins of these crises are not related to Mintos (Covid-19 pandemic, war in Ukraine), they have clearly exposed the problems at Mintos. Especially in 2020, there have been numerous actions and entanglements that have not painted a good picture with regards to the integrity of the platform. Mintos, operated by AS Mintos Marketplace, was founded in January 2015 and is one of the most experienced P2P platforms in Europe. In its home market, the platform is supervised and monitored by the Latvian Central Bank (Latvijas Banka). No Red Flags present. Since August 2021, AS Mintos Marketplace has held an Investment Firm Licence issued by the Latvian Central Bank. Through its regulatory status, the platform is subject to the requirements of the Markets in Financial Instruments Directive (MiFID II). As a result, investor accounts are protected by up to EUR 20,000 (90% of net loss) through the Latvian investor compensation scheme, in the event of platform insolvency or misappropriation of investor funds. Potential loan defaults by loan originators are not covered by this scheme. Through its regulatory status, Mintos is also required to meet a high standard of compliance and transparency, including the regular publication of financial statements audited by KPMG Baltics, which provide insight into the platform’s financial stability. Under MiFID II regulation, Mintos is required to keep investor funds and financial instruments separate from the platform’s own assets. In the event of insolvency, these funds are protected from enforcement proceedings and cannot be used to settle claims against third parties. Unlike traditional bank deposits, there is no entitlement to compensation through a deposit guarantee scheme. Investors should therefore be aware that invested capital is subject to a real risk of loss, that returns are not guaranteed and that it may not be possible to recover the full amount invested. In the past, Mintos had to navigate several crisis situations, including the COVID-19 pandemic and the war in Ukraine. COVID-19 Pandemic: Mintos responded early to the crisis with a series of measures, including a cost reduction of approximately 40%, the dismissal of 45 employees and a significant cut to marketing budgets. Two measures in particular proved controversial. The schedule extension, originally introduced in October 2019, was expanded in March 2020 to 6 intervals of 31 days each. It was also made possible to further postpone loans already in default. In doing so, Mintos not only acted against its own terms of use but also prioritised the interests of loan originators over those of investors. Equally controversial was the introduction of new terms and conditions in August 2020, which included a provision requiring investors to share in legal costs in the event of loan originator defaults. This shift of liability from Mintos to the investor was met with significant criticism from the investor community. War in Ukraine: Following the outbreak of the war in Ukraine in February 2022, Mintos suspended all new investments in Russian and Ukrainian loans. A total of eight loan originators were affected. These were immediately removed from Mintos strategies and both Russian and Ukrainian loans could only be traded via the secondary market going forward. The financial stability of a P2P platform is a key risk factor. Is Mintos able to operate profitably? And what conclusions can be drawn from the balance sheet? Annual Report Auditor: KPMG Baltics Established and independent audit firm (Top 10 worldwide). Standard: IFRS Internationally recognised standard. Transparent and comparable. The following figures are based on the Mintos annual report for 2025. The report was prepared by KPMG Baltics and audited in accordance with IFRS standards. The figures therefore carry a certain degree of credibility. Mintos has recorded a loss of around EUR 2 million in each of the past two financial years. Although revenue increased by 17% to EUR 14.1 million, operating expenses also continued to rise. In particular, there were significant increases in employee costs (EUR 6.5 million; previous year: EUR 5.1 million) and investments in new IT systems (EUR 3.8 million; previous year: EUR 2.8 million). The strong growth pace of Mintos is clearly reflected in its balance sheet figures. While the company is already able to generate positive operating cash flow (EUR 1.38 million), net cash flows from investing activities are still significantly higher (EUR 3.72 million). To offset ongoing losses, Mintos carried out a capital increase in the first half of 2026, injecting an additional EUR 2.2 million into the company. The funds came from a funding round in which private investors contributed EUR 2.8 million. The equity ratio decreased to 36.3%, but remains at an acceptable level. In addition, both the liquidity ratio (1.37) and the debt ratio (1.75) have worsened. For a growth-oriented company, the balance sheet is not alarming, but also not comfortable. As long as growth continues and fresh capital flows in, there should be no issues. At the shareholder level, Mintos has always had significant overlaps with many of its lending companies. This creates the issue that measures taken often serve the interests of shareholders first and investors only second. Particularly in the period before obtaining the IBF license, there were several instances where apparent conflicts of interest resulted in disadvantages for investors. With an outstanding portfolio of around EUR 100 million, the Finko Group was the largest non-bank lender on Mintos at the beginning of 2020. The year before, the group — which was represented on Mintos through seven lending companies — had financed EUR 366 million in consumer loans and generated a profit of EUR 17.6 million. One year later, little more than an empty shell was left of the group. Some lenders had their licenses revoked under dubious circumstances (such as Varks in Armenia), others filed for bankruptcy (Metrokredit and Kiva in Russia), and some were sold off for a fraction of their value to competitors with the same shareholders (such as Sebo in Moldova). As a result, no funds remained to honour the previously promoted buyback guarantees. With an outstanding portfolio of EUR 30 million on Mintos, the Armenian lender Varks was the largest lender within the Finko Group at the time its license was revoked in March 2020. Although there were already obvious issues with the lender from the Armenian central bank at that time, Varks was still promoted by Mintos through a variety of measures, including forward flows and cashback campaigns. In the case of Varks, Mintos was well aware of the lender’s financial situation and problems with the central bank. Yet, no measures were taken or initiated to protect investors funds. In the end, it was publicly communicated that a two-year repayment plan was in place, serving the outstanding obgligations by the end of 2022. In June 2024, around EUR 10 million in investor funds had still not been repaid. Mintos now forecasts a loss of 50% to 25%. Due to the COVID-19 pandemic and the war in Ukraine, Mintos experienced numerous problems with lenders, many of whom were subsequently unable to meet their outstanding obligations to investors. At times, up to EUR 150 million of investor funds were in recovery, affecting around 30% of Mintos’ total loan portfolio. For a successful investment on Mintos, it is therefore essential that investors independently examine the risk profile of each lender. To assess the financial stability, the following table provides an overview of the current financial figures. You can check out the lender overview and comparison page to learn more about the applied KPIs and their interpretation. In this section, I have listed the biggest advantages and disadvantages of Mintos. With a favourable economic situation behind them, investors have been able to regularly achieve double-digit returns. However, investors had to pay the price for this rapid growth due to a combination of inadequate due diligence and macroeconomic events. As a result, more than EUR 140 million are still in the recovery process in 2024. Mintos itself is already expecting a loss of at least EUR 64 million. Because the overall performance of the Mintos portfolio shows that a diversified approach across multiple lenders does not work, investing in P2P loans is only recommended for advanced investors who are able to evaluate individual lending companies. Apart from that, asset classes like fractional bonds offer a much more interesting alternative for investors on Mintos. New investors receive a tiered Bonus with the code INVEST26. €25 from €1,500, €35 from €2,500, €75 from €5,000, €175 from €10,000 and €500 from €25,000. Qualifying products: Loans, Bonds, ETFs, Real Estate and Crypto-ETPs (Mintos Smart Cash excluded). Already invested in Mintos? Or looking for similar platforms? Here are three Mintos alternatives from the P2P market. Income Marketplace: An unregulated P2P marketplace headquartered in Estonia, which markets itself through innovative security features that are designed to protect investors from underperforming loan originators. Similar to Mintos, Income Marketplace follows a marketplace model with a wide range of international loan originators. Attractive combination of high interest rates and high liquidity. More information in my Income Marketplace review. PeerBerry: A P2P marketplace incorporated in Croatia, working closely with partners from within the Aventus Group. Compared to Mintos, PeerBerry is notably more focused in its approach and stands out through a strong performance during times of crisis and a reliable repayment quality. More information in my PeerBerry review. Afranga: A regulated P2P marketplace based in Bulgaria, holding an ECSP licence. Compared to Mintos, Afranga is notably smaller and more focused in its approach, but offers competitive interest rates and a clean performance record with no capital losses for investors to date. A good fit for investors looking to add a regulated niche platform to their portfolio. More information in my Afranga review. On my blog, investors can find a detailed breakdown with the best Mintos Alternatives in 2026. You can find other Mintos alternatives in the P2P Platform Comparison page. Mintos is Europe’s largest P2P marketplace, headquartered in Riga, Latvia, operational since 2015. In addition to P2P loans, investors can also invest in ETFs, bonds, real estate, a money market fund, and regulated crypto ETPs. Yes. Mintos has been regulated by the Latvian financial authority (FCMC) under MiFID II since August 2021. Investor funds are protected up to €20,000 by the Latvian investor compensation scheme in case of platform insolvency. According to Mintos, the net return on P2P loans ranges between 10% and 12%. My personal return after five years stands at 10.79% — dropping to 7.22% once I factor in over €1,000 stuck in the recovery process, which I’ve written off as a loss after two years without repayment. Loan originator defaults can significantly impact your actual yield. The main risk lies in loan originator defaults. During the COVID-19 pandemic and the war in Ukraine, up to €150 million of investor funds were tied up in recovery at times. Carefully selecting loan originators is therefore essential. Yes. New investors who register via my affiliate link and invest at least €1,500 within the first 30 days receive a €25 sign-up bonus. I’m Denny Neidhardt, the founder of re:think P2P. On this blog, I help retail investors make smarter, well-informed investment decisions in the world of P2P lending. Since 2019, I’ve been publishing in-depth analyses, platform reviews, and risk assessments to bring more transparency to this investment space. My goal is to challenge marketing claims, question developments, and empower investors with honest, independent insights.
What is Mintos?

Mintos at a Glance
Founded / Started:
May 2014 / January 2015
Legal Name:
AS Mintos Marketplace (LINK)
Headquarter:
Riga, Latvia
Regulated:
Yes (Financial and Capital Market Commission)
CEO:
Martins Sulte (May 2014)
Assets Under Management:
EUR 750.5+ million
Number of Investors:
600,000+
Expected Return:
10.4%
Risk Score:
6.2 / 10 (Rank 11 of 31) | View Methodology
Primary Loan Type:
Consumer Loans
Collateral:
Buyback Obligation
Origin Story
 The Latvian Martins Sulte, one of the founders and CEO of Mintos, was in the final stages of his MBA studies in 2014. At the time he wrote down some ideas about what he could do after graduation.
Business Model

Mintos On-Site Visit
Mintos News
Shareholder and Management
Mintos Shareholder

Mintos Management

Sign Up and Bonus
Mintos Bonus
Investing on Mintos
Loan Offering
Fractional Bonds
High-Yield Bonds Portfolio
Mintos Core ETF Portfolio
Mintos Smart Cash
Crypto Investments on Mintos
Costs and Fees
Expected Returns
Auto Invest

Mintos App
Mintos Taxes
Mintos Risks
Platform Risk
Red Flags 0
Regulation and Licence

Segregation of Funds and Deposit Protection
Mintos in Crisis Situations

Financial Stability
Profitability

Balance Sheet

Lender Risk
Finko Group
Varks

Lender Analysis
Lender Year Audited Profit ROA Equity Liquidity Losses Score Eleving Group (LU) 2025 BDO EUR 29.2M 5.5% 18.3% 3.42 21.8% 80 Hipocredit (LT) 2025 Nexia EUR 1.1M 4.2% 15.8% 14.52 80 Gocredit (MX) 2025 Unaudited EUR 4.4M 10.1% 44.2% 7.35 13.8% 79 Credifiel (MX) 2024 RSM EUR 7.1M 6.0% 35.6% 1.16 14.8% 78 Financiera Mexi (MX) 2024 BDO EUR 1.8M 3.0% 35.0% 2.66 11.0% 78 Placet Group (EE) 2025 KPMG EUR 5.6M 6.3% 38.4% 4.76 20.3% 77 IuteCredit (MD) 2024 Baker Tilly EUR 2.4M 4.1% 32.9% 2.74 17.5% 75 Mozipo Group (RO) 2024 Unaudited EUR 178K 3.3% 41.6% 1.92 12.5% 75 Sun Finance Group (LV) 2025 BDO EUR 58.3M 20.7% 33.0% 3.54 40.0% 75 ESTO (EE) 2024 Unaudited EUR 11.3M 16.9% 33.4% 2.71 10.6% 74 Finclusion (KE) 2025 PwC EUR 31K 0.3% 29.2% 13.9% 74 Eleving (BW) 2025 BDO EUR 1.3M 4.6% 22.4% 14.9% 73 Eleving (GE) 2025 Unaudited EUR 1.7M 5.6% 74.9% 2.22 19.5% 72 IuteCredit (MK) 2024 Moore Stephens EUR 2.0M 5.4% 15.4% 7.41 27.5% 71 Mozipo Group (LT) 2025 Grant Thornton EUR 359K 2.0% 29.6% 20.4%* 71 Eleving / Mogo (MD) 2024 BDO EUR 1.3M 6.9% 12.3% 14.4% 70 Eleving / Sebo (MD) 2025 BDO EUR 2.6M 8.7% 31.2% 31.0% 70 ID Finance (ES) 2025 EY EUR 20.4M 15.4% 23.5% 2.23 59.6% 70 Cash Credit (BG) 2024 Einzelprüfer EUR 265K 4.0% 55.4% 1.80 1.7% 69 DelfinGroup (LV) 2025 BDO EUR 9.6M 6.6% 18.5% 0.45 33.1% 67 Iute Group (EE) 2025 KPMG EUR 9.9M 2.1% 15.8% 24.5% 66 Eleving / AS Mogo (LV) 2024 BDO EUR (969K) (2.6%) 72.4% 2.29 43.7% 64 BB Finance (EE) 2024 KPMG EUR 1.1M 5.0% 18.0% 25.8% 63 Restock Tech Group (ID) 2025 Unaudited EUR 137K 1.6% 17.5% 6.72 8.6% 63 Eleving (AM) 2024 Unaudited EUR 3.5M 20.0% 61.5% 1.58 7.7%* 62 Eleving (LT) 2025 Unaudited EUR 213K 0.9% 16.3% 2.46 5.0% 61 Pinjam Yuk (SG) 2025 Unaudited EUR 1.5M 5.2% 42.8% 1.73 79.0% 60 ID Finance Gruppe (ES) 2024 EY EUR 6.6M 4.2% 16.0% 61.5% 58 Eleving (AL) 2025 Unaudited EUR 6.0M 14.5% 30.2% 23.1% 57 Eleving / FINMAK (MK) 2025 Unaudited EUR 4.4M 17.0% 53.6% 30.4% 57 MK Kredit (RO) 2025 Unaudited EUR 2.0M 3.8% 19.4% 10.2% 57 Watu Credit (UG) 2024 Unaudited EUR 8.3M 9.1% 28.9% 18.7% 57 Vivalia (MX) 2025 Unaudited EUR 97K 0.2% 46.2% 15.6% 56 Evergreen Finance (GB) 2025 Unaudited EUR 1.7M 5.2% 22.4% 1.59 33.6% 55 IuteCredit (AL) 2024 Unaudited EUR 4.7M 5.6% 26.7% 1.42 35.7% 55 Credius (RO) 2025 Unaudited EUR 1.7M 7.6% 40.7% 35.6% 52 Mogo (KZ) 2025 Unaudited EUR 8.1M 7.2% 16.3% 18.4% 52 MK Kredit (MD) 2025 Unaudited EUR 241K 1.0% 32.7% 24.7% 51 Sun Finance (SE) 2025 Einzelprüfer EUR 2.5M 9.2% 9.6% 1.11 65.7% 49 IDF Eurasia (KZ) 2024 Unaudited EUR 2.6M 1.2% 18.7% 1.37 39.4% 46 Monefit (EE) 2025 Unaudited EUR 88K 0.1% 10.2% 7.3% 46 Eleving (EE) 2025 Unaudited EUR 16K 0.0% 7.6% 0.99 20.9% 45 Creditstar (FI) 2025 Unaudited EUR 96K 0.1% 2.9% 10.5% 41 IuteCredit (BG) 2024 AELB Bulgaria EUR (1.2M) (8.1%) 8.3% 1.21 57.8% 41 Hipocredit (LV) 2025 Unaudited EUR 206K 1.2% 14.6% 8.12 38 Eleving / mogo (LT) 2024 ROSK EUR (667K) (2.6%) 7.8% 32 ESTO (LT) 2024 Tezaurus EUR (1.1M) (19.9%) (57.7%) 43.7% 26
Advantages and Disadvantages
Summary Mintos Review
 Mintos is the market leader in the European P2P lending environment. This status has been achieved through a highly scalable business model with externally connected lenders.
Mintos Alternatives
FAQ Mintos Review

Mintos Review 2026
Last Update: 27 August 2026
★★★★★
(3.4)
New Investor Bonus
Skin in the Game
Previously invested from October 2017 – October 2022 (total return: 7.22%)
26. August 2026
22. July 2026
26. May 2026
★★★★★
(3.4)
New Investor Bonus
In case further losses from outstanding recoveries are written off in the future, the net return would be adjusted downward accordingly.
When paying taxes in your county of residence, the withheld taxes can usually be deducted from the overall balance. This means that the effective taxation rate will be the same as it has been before when investing into claim rights. To get access to the relevant data, Mintos offers to download tax reports and income statements from the platform.
Safety Score
Rank 11 of 31
6.2
/ 10
Medium Risk
Regulation and Licensing
15 / 15
Financial Stability
16 / 20
Transparency and Disclosure
15 / 15
Loan Portfolio and Investor Losses
3 / 25
Track Record and Crisis Behaviour
13 / 25
The Safety Score assesses platform risk only. Lender risks and country-specific risks are not covered and must be evaluated separately.
★★★★★
(3.4)
New Investor Bonus
Affiliate Links / Conflict of InterestDisclaimer
This article contains affiliate links. If you register and/or invest through one of these links, the operator receives a commission. The compensation has no influence on the opinion or the evaluation of the platform. Potential conflicts of interest can be looked up on the “P2P Portfolio” page.
Investments in P2P loans involve risks and may result in the complete loss of the invested capital. Past performance is not a reliable indicator of future developments. The following content is provided for informational purposes only and does not constitute investment advice. Despite careful research, no guarantee is given for the accuracy, completeness, or timeliness of the information provided. No liability is accepted for any financial losses or investment decisions made based on the information presented here. For more details, see the full disclaimer.
✅ What is Mintos?
✅ Is Mintos regulated?
✅ What returns can I expect from Mintos?
✅ What are the biggest risks at Mintos?
✅ Is there a bonus for signing up with Mintos?
Hi, thank you for the blog and the info, I am looking to divesify my portfolio and I will deffinetly open Esketit shortly and Peerbeery is next and will use your referal link. I have started Bondora as well in 2017, the porfolio was a disaster and stopped it (lost only €1) but I made some profits with their Go&Grow. I have just deposited 1k again to have a chance to win their prize :). I stated Mintos in 2018 where I had 10k, from August 2018 to 2021 or so when I took out all my money and left only my profits, but I didn’t really look after it. I added again 10k to Mintos in a few steps this summer and I think you are doing it wrong with Mintos. I did experience loss as well of around €700 but this was due to buying discounted loans during the pandemic from companies I knew were bad and I also did not respect my own strategy. Losses were mostly because of my greed, but… the discount I made on premium when buying those loans was over €1000, so I did not actually lose. Soon after the cracks happened I was exposed with 1.5k but half of it has been recovered so fine for me. Some might still be recovered. It’s true that lately I login daily to the platform and buy only manually, but my return is 19.05% (add 2% with campaigns and bonuses). I made more money on SM than interest. THere are some good loan originators such as Esto, Placet Group (small but always on profit), Delfin and Iute. I invest in most of the listed LOs to diversify but in the shady ones I only do invest 1-2% max and if I find discounted loans on SM or they offer good return (Credistar has loans at 15.5% up to 17.5%, I have about 2% of my portfolio in those). I always try to get the highest yields from each LO and I have a strategy for it. :). My current estimated average return is 13.10%. But can’t wait to try out the other ones.
Hi Lavinia,
thanks for commenting and sharing your experiences so far.
Best, Denny
Hi Denny,
Mr. Harrington has made for years a very frequent and appreciated update of his personal loan originators rank in Mintos, fixed from official data: https://explorep2p.com/mintos-lender-ratings/. It was great but in the last year he’s time by time less active. Why don’t you launch your personal one? we’ll surely be glad tò you!
Hi Mario,
thanks for hinting at this idea. To be honest, this involves a lot of work. Not just to set it up, but also maintaining the rating. I would rather manage my resources differently and cover different platforms instead.
Kind regards,
Denny
Pure maffia still owing me money.
offering buyback but not being able to collect the money.
they knew varks was in trouble at that time even giving higer rates and coming with al new constructions..
its a goddame miracle this company can get away with this rubbish.
Hi Rob,
thanks for contributing to my Mintos review.
You are right, the whole Varks and Finko case has indeed been a very shady chapter in Mintos’ long history.
Best, Denny