

Last Update: 14 August 2026
New investors receive a €5 bonus plus 3% cashback on all investments made within the first 30 days after successful registration. I am invested with my own funds at LANDE since December 2021. Since then, I achieved a total return (XIRR) of 9,96%. My outstanding portfolio on the platform stands at 15.294 €. The business model of LANDE intends to close the underfinanced gap among small and medium-sized enterprises in the agricultural sector. According to a study by the European Investment Bank this gap has been between EUR 19.8 billion and EUR 46.6 billion in the European Union during 2020. Although LANDE is a comparatively new platform, it offers attractive conditions for investors who want to diversify their portfolio outside from traditional consumer loans. The platform also received the European crowdfunding service provider licence at the beginning of 2024, allowing the company to operate throughout Europe. All key facts and figures about LANDE at a glance. For those who prefer watching over reading, take a look at my LANDE video review (August 2024): The origin of LANDE goes back to 2008. That year, Edgars Tālums (left) established the non-bank lender Latvijas Hipotēka. This company specialized primarily in financing mortgage loans. The loan financing came primarily from a small circle of wealthy private investors. Some of them are still cross-financing LANDE’s loan projects today (anchor investors). In order to help their investors to monitor their loan portfolios, the company created the first prototype of what is now known as the LANDE P2P platform in 2017. In July 2020, a decision was made to allow also smaller retail investors to finance the loan book, which enabled LANDE to further diversify their funding sources. The P2P platform was born. LANDE is a P2P lending platform focused on the agricultural sector. The platform acts as an intermediary between investors seeking a return on their capital and farmers looking to take out loans for their operations. In line with the classic P2P model, LANDE sources and assesses borrowers independently before listing the loans on the platform for financing. LANDE generates revenue on two levels: Through a classic origination fee charged upon successful financing on the platform (up to 10% p.a.) and through a servicing fee calculated on the outstanding principal (between 1% and 4% p.a.). With its business model, LANDE generated revenue of EUR 1.9 million in the 2024 financial year. Although I have known LANDE founder and CEO Nikita Goncars through numerous personal conversations since 2020, the first in-person meeting only took place in June 2024 in Riga. The impression I had formed of Nikita online was confirmed in person: Calm, competent and measured in his views. The conversation covered a wide range of topics, including the operational adjustments made in recent months, the revised IT infrastructure, the development of individual loan markets and the tightened approach to debt recovery. The financial figures for 2023 and the strategic goals for the current year were also discussed. P2P lending is a dynamic asset class where investors should stay continuously informed. You will find the latest news on LANDE on my P2P lending news page, where I cover other P2P platforms as well. LANDE has published its Performance Report for July. Across its four core markets, the platform financed 67 projects worth €2.1 million, averaging €31,389 per project. The average return earned by investors during the month was reportedly 12.29%, excluding cashback campaigns and other bonuses. According to LANDE, it has observed a continuous decline in loans that are more than 30 days overdue since April. The share of loans secured by land and machinery stood at 95% in Latvia and 100% in Lithuania, Romania, and Poland in July. According to LANDE, livestock- and harvest-secured loans continue to show the highest default rates, which is why the platform is increasingly moving away from this type of collateral. On October 5, LANDE will update its Terms and Conditions. The key change is the introduction of a new inactivity fee. Investors will now be charged €10 per month during the first twelve months of inactivity, increasing to €50 per month from the 13th month onwards. The fee only applies if two conditions are met simultaneously. First, no new investment has been made on either the Primary or Secondary Market during the previous twelve months. Second, there must be available cash in the account from which the fee can be deducted. In plain terms: If you are simply letting your portfolio run off, you should regularly withdraw any available cash. If you do not agree with the change, you can terminate your account by contacting LANDE support via email until 4 October 2026. Without objection, the new terms will automatically apply. LANDE has published its monthly performance report for June. Across its four core markets, the platform financed 69 projects with a total volume of EUR 2.33 million, averaging EUR 33,753 per project. According to LANDE, investors earned an average annual return of 13.01% during the month, excluding any cashback campaigns or other bonuses. The platform also welcomed 176 new investors in June, while cumulative interest paid to investors exceeded EUR 5 million for the first time. Personally, I have earned EUR 2,708 in interest since investing in December 2021, corresponding to a total return of 9.96%. Another positive development is the decline in the number of defaulted loans. In absolute terms, the defaults (90+ days) fell from 126 to 111 loans. Based on the currently outstanding portfolio, defaulted loans now account for approximately 10.7% of the total portfolio. Alternatively, you can subscribe to my Telegram channel or WhatsApp group (both free of charge) to receive real-time updates as soon as new developments emerge. Who are the main shareholders and management executives behind LANDE? Let’s have a look! A look at the Latvian company register reveals that the platform is currently owned by four different shareholders. 88.6% of the shares are held by LANDE CEO and co-founder Nikita Goncars, who is therefore also the ultimate beneficial owner (UBO) of the platform. The remaining shares are held by VAUBAN NOMINEES LIMITED with 4.6%, the LANDE investors with 4.5% and the BADideas Fund with 2.2%. He graduated from BA School of Business and Finance, one of the leading business schools in Latvia. He was then co-founding several companies in the financial, real estate and agricultural sectors. This was followed in June 2019 by the launch of LANDE, formerly LendSecured. On this page, investors can look at the other platform’s team members. To invest on LANDE, investors must meet three requirements: The registration process at LANDE is fairly simple and intuitive. After opening the account via email, the KYC (Know-Your-Customer) and AML (Anti-Money-Laundering) questionnaires have to be completed. This is followed by the verification of identity. Also legal entities have the opportunity to sign up on LANDE.
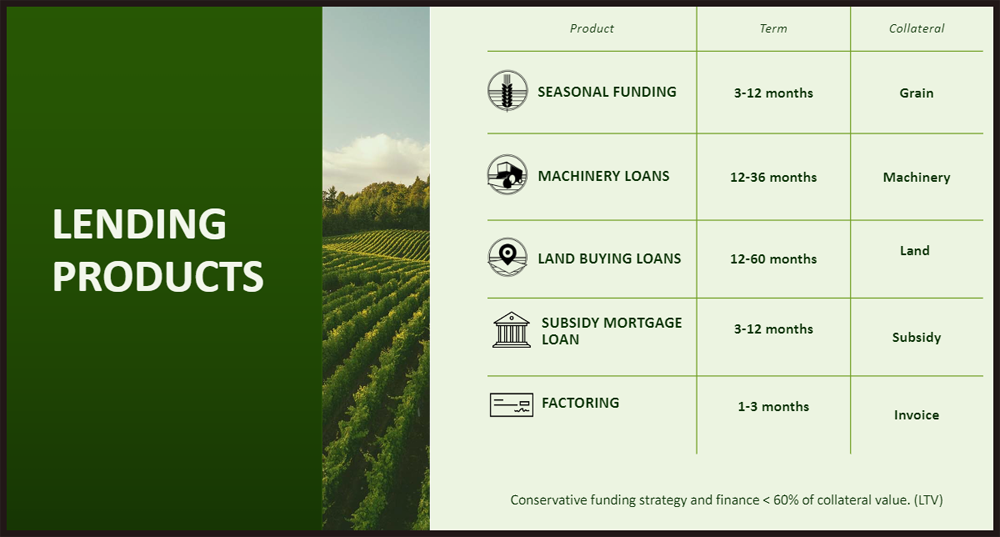
New investors receive a €5 bonus plus 3% cashback on all investments made within the first 30 days after successful registration. A platform overview with all bonus offers and cashback promotions can be found on the bonus page. How does LANDE work and what should investors know and consider when investing on the plaform? In the following sections of my LANDE review you will find all the necessary information that you need. The loans that are offered on LANDE can be segmented into five different areas: In addition, two less common loan products are subsidized mortgage loans as well as factoring loans. Most of the agricultural loans offered on LANDE come from the Latvian market. At the same time, LANDE also offers loans from Lithuania and Romania. Here are some average numbers from the LANDE loan portfolio: The loan-to-value (LTV) is 44%, the interest rate is 10.6%, the loan term is 18 months and the loan amount is EUR 23,000. There are no fees or hidden costs for retail investors on LANDE. Neither for deposits or withdrawals, nor for the functionalities when investing on the platform. If you invest in agricultural loans on LANDE, you can achieve a return of up to 14% (taking cashback campaigns into account). The interest rates of the loans can fluctuate depending on the market phase. Usually, they are between 10% and 12%. Possible loan defaults should be taken into account in the overall assessment, which can have a negative impact on the expected return. My personal investment experience with LANDE goes back to December 2021. Since then, I have achieved a total return of 9.46% (July 2024). LANDE has launched an Auto Invest feature in December 2021. The Auto Invest is divided into “Basic” and “Advanced”. With the advanced LANDE Auto Invest, investors have several options to choose from. For example, the interest rate, the loan term, the loan-to-value (LTV) or the type of collateral can be defined more precisely. In 2024, LANDE added two more elements with the repayment type and the borrower countries. In addition, the minimum investment amount for the advanced Auto Invest strategy has been reduced from EUR 250 to EUR 100 per loan. LANDE integrated a secondary market in October 2020, where investors can sell their investments or buy already funded loans. Contrary to the minimum investment amount on the primary market (EUR 50), investors can purchase loans starting from EUR 2. No fees apply. Investors that want to diversify their portfolio on a broader scale and that aim to allocate their funds a lot faster, the secondary market on LANDE can be a good place to start. Note: The LANDE secondary market was relaunched in June 2024. Investors can find out about the new rules in this article. LANDE does not offer any kind of buyback guarantee. This is common practice for platforms that offer loans backed by collateral. The loans on LANDE are secured by mortgage with an average LTV of 43%, which is extremly low-risk. For comparison: Real estate platform EstateGuru offers an LTV average of 65%. Whether the collateral may be overvalued can only be assessed when loans default and the collection processes have increased on the platform. For the tax declaration, investors can find the “Balance” tab in the main menu, where a tax report for the respective year can be downloaded as a PDF (“Income Statement”). This information can then be used to be submitted to the tax office. Investors should look very carefully at the potential risk factors when evaluating a P2P platform. What is it that investors need to be aware of when it comes to LANDE? Where are the underlying risks and how are they assessed? The get an idea about potential risk elements involved at LANDE, the platform published a list of aspects that investors need to be aware of. This includes market risk, liquidity risk, platform risk and many more. The platform, operated by the Latvian company “SIA LANDE Platform”, launched operations in July 2020. In its domestic market, the platform is supervised and monitored by the Latvian financial supervisory authority (Latvijas Banka). No Red Flags present. In February 2024, the Latvian financial supervisory authority (Latvijas Banka) approved the licence allowing LANDE to operate as a service provider under the European Crowdfunding Regulation (ECSP). This enables the platform to offer its services across the EU under a unified regulatory framework, without requiring a separate authorisation in each member state. Unlike MiFID II-regulated platforms, investors have no entitlement to compensation through an investor compensation scheme. Loan defaults or a potential insolvency of borrowers are also not covered by the regulation. The ECSP regulation does, however, prohibit platforms from listing projects connected to affiliated companies or insiders. Through its regulatory status, LANDE is also required to meet a high standard of compliance and transparency, including the publication of audited financial reports. The ECSP licence requires LANDE to maintain a strict separation between investor funds and the company’s own operating funds. For this purpose, the platform works with Lemonway, with funds held at BNP Paribas. This means that in the event of LANDE ceasing operations, investors retain access to their funds and loan repayments can continue in an orderly manner. Investments offered through LANDE are not covered by a national or European deposit guarantee scheme. Investors should therefore be aware that invested capital is subject to a real risk of loss, that returns are not guaranteed and that it may not be possible to recover the full amount invested. The war in Ukraine had a paradoxical short-term effect on LANDE. Due to severe disruptions to global grain trade, commodity prices rose sharply. At its peak, one tonne of wheat was trading at more than EUR 400, representing an increase of approximately 60%. At that time, approximately 50% of the outstanding loan portfolio was secured by grain purchase contracts. As a result, the value of these collaterals increased significantly, while the default risk for investors declined at the same time. The financial stability of a P2P platform is a key risk factor. Is LANDE able to operate profitably? And what conclusions can be drawn from the balance sheet? Annual Report Auditor: Orients Audit & Finance Regulated audit firm. Standard: Latvian GAAP Local standard, not internationally comparable. According to the latest financial report, the LANDE platform generated a profit of EUR 206,485 in the 2025 financial year. As a result, the Latvian P2P platform has remained profitable for the second consecutive year, with profit increasing slightly compared to the previous year (EUR 196,742). These figures indicate that LANDE is pursuing a conservative and sustainability-oriented growth strategy that is not dependent on excessive leverage or external debt financing. LANDE offers highly collateralized agricultural and development loans on its platform. The collateralization breaks down as follows: Investors should be aware that loan defaults are part of the business and cannot be avoided in the long term. The average loan-to-value ratio on LANDE is 44%. If farmers are no longer able to repay their loans, the loans appear to be well secured. The first defaulted loans were successfully and 100% recovered. This means that investors have not yet suffered any losses on their investments. The registered collateral has always had a sufficient risk buffer. In this section I have listed the most important advantages and disadvantages of LANDE. LANDE is a regulated crowdfunding platform based in Latvia that operates in an exciting and rapidly growing niche with its positioning in the agricultural sector. This not only offers great growth potential for the platform, but also creates real value for investors in terms of diversification. Due to the strong growth of the platform, there was a temporary overload of operational processes, which affected IT, the secondary market and the collection process, among other things. However, LANDE has been much more stable again since summer 2024. The performance of the loan portfolio is also within a good range. Anyone who is looking for an additional alternative to their P2P portfolio, apart from traditional consumer loans, LANDE is an emerging platform worth considering. New investors receive a €5 bonus plus 3% cashback on all investments made within the first 30 days after successful registration. Already invested in LANDE? Or looking for similar platforms? Here are three LANDE alternatives from the P2P market. InSoil Finance: The largest P2P platform in the Baltics with a focus on agricultural loans. Similar to LANDE, InSoil Finance targets investors that are looking to finance farmers and agricultural businesses, with loans that are notably secured through farmland and heavy machinery. Compared to LANDE, InSoil Finance offers a broader geographical diversification across multiple European markets. More information in my InSoil Finance review. Crowdpear: A regulated crowdfunding marketplace based in Lithuania. Focus on mortgage-secured real estate loans from the Baltic region. Crowdpear was built by the same team behind the P2P marketplace PeerBerry and stands out through a notably strong loan portfolio performance and a high level of transparency. More information in my Crowdpear review. Debitum: A regulated P2P marketplace based in Latvia. Focus on business loans. Like LANDE, Debitum targets investors that are looking to invest in secured loans outside of classical consumer lending. With the Latvian Forest Development Fund and Baltic Terra, Debitum also offers a notably strong focus on the forestry and timber industry. More information in my Debitum review. You can find other LANDE alternatives on the P2P Platform Comparison page. LANDE (formerly LendSecured) is a Latvian P2P platform regulated under the EU Crowdfunding Regulation (ECSP) since February 2024, where investors can invest in secured agricultural loans. Returns reach up to 12%. The platform launched operationally in July 2020. Interest rates typically range between 10% and 12% depending on market conditions. My personal total return since December 2021 stands at 9.46%. Potential loan defaults should be factored into return expectations, even though no capital losses have occurred to date. LANDE does not offer a buyback guarantee. Instead, agricultural land, machinery, and crop yields serve as collateral. The average loan-to-value ratio is just 44%, which is significantly lower than the industry average on real estate platforms. Yes. The secondary market was originally introduced in October 2020 and relaunched in June 2024 after a longer break. Investors can buy or sell already financed loans from as little as €2, with no fees charged. Yes. New investors registering via my partner link receive 3% cashback on all investments made within the first 30 days. On a €10,000 investment, that equals €300 cashback. I’m Denny Neidhardt, the founder of re:think P2P. On this blog, I help retail investors make smarter, well-informed investment decisions in the world of P2P lending. Since 2019, I’ve been publishing in-depth analyses, platform reviews, and risk assessments to bring more transparency to this investment space. My goal is to challenge marketing claims, question developments, and empower investors with honest, independent insights.
What is LANDE?
 LANDE (formerly LendSecured) is a Latvian P2P platform where investors can finance a variety of highly collateralized agricultural and development loans, while earning a return of up to 12%. The operational launch of the platform took place in July 2020. The first loans have been issued in September 2020.
LANDE at a Glance
Founded / Started:
December 2009 / January 2021
Legal Name:
SIA LANDE Platform (LINK)
Headquarter:
Riga, Latvia
Regulated:
Yes (ECSP License)
CEO:
Nikita Goncars (June 2019)
Assets Under Management:
EUR 35.6+ million
Number of Investors:
10,000+
Expected Return:
11.2%
Risk Score:
7.7 / 10 (Rank 4 of 31) | View Methodology
Primary Loan Type:
Agricultural Loans
Collateral:
Mortgage
The Origin Story
 In 2011, Nikita Goncars joined the company as a second shareholder and business partner. Over the years, collateralization by agricultural land and smaller residential properties developed into a core competence of the company.
Business Model

LANDE On-Site Visit
LANDE News

Shareholder and Management
LANDE Shareholder
 Who owns LANDE? The platform is operated by the Latvian company “SIA LANDE Platform”, which was founded on 14 March 2022.
LANDE Management
 Nikita Goncars is the CEO, co-founder and strong man behind Latvian platform LANDE.
Sign Up and Bonus
LANDE Bonus
Investing on LANDE
Loan Offering
Costs and Fees
Expected Returns
Auto Invest
 With the basic Auto Invest, no criteria can be selected. This way, investors automatically invest in every loan that becomes available. The minimum investment amount is EUR 50.
Secondary Market

Buyback Guarantee
LANDE Taxes
 Generally, interest income generated by loan financing is considered investment income and must be reported as such on the tax declaration. Unlike other platforms, LANDE does not withhold any taxes at the moment.
LANDE Risks
Platform Risk
Red Flags 0
Regulation and Licence
Segregation of Funds and Deposit Protection
LANDE in Crisis Situations
Financial Stability
Profitability

Balance Sheet
 LANDE has very strong balance sheet metrics. Despite slight deteriorations compared to the previous year, the equity ratio (61.7%), the liquidity ratio (1.93), and the debt ratio (0.62) all remain at healthy and comfortable levels.
Loan Default Risk

Advantages and Disadvantages
Summary LANDE Review
 What is the final verdict of my LANDE review and my personal opinion of the platform?
LANDE Alternatives
FAQ LANDE Review
I have decided to give Lande a try but it is terrible. Deposited money 20 days ago, settup the auto-invest, but is not working. I have double checked it, set-up a second one, still nothing. No loans are ever available to invest in. So we’re talking about 20 days of full cash drag… never seen anything like this. They should pause new users, I just feel they are using my money for free.
Thanks for sharing your feedback regarding Lande. I can’t comment on your AI settings, which may compromise loan selection further. In general, there is a shortage of new loans recently. Everyone is affected. Hence, I can understand your frustration of not getting your funds invested. Have some patience or consider buying from the secondary market to start off, which also helps to pick up loans for less than EUR 50.
Thank you for your question Nuno,
Agricultural land is an extremely liquid asset in the Baltics and EU. Due to the high deficit, most land plots are sold above the valuation price on the auctions.
https://eng.lsm.lv/article/economy/economy/farmland-prices-tripled-over-decade-in-latvia.a461551/
Also, compared with residential real estate or construction, there are no risks of unfinished construction, company bankruptcy, etc. Land is a finished asset with a clear and stable valuation.
Dont you think Lande is an EXTREMELY dangerous platform ?
All its loans are secured by land and other hard to sell and legally complicated assets?
I mean is Estateguru is taking years or maybe decades to recover failed investments and this is with houses I can only imagine Lande trying to sell some farmer’s field to recover investor’s money
Am I the only one thinking Lande is a tricking nuclear time bomb ?
How Lande is recovering defaulted assets will be interesting to watch, for sure. But so far, I don’t consider Lande being riskier than other comparable alternatives.