

Last Update: 4 September 2026
About the re:think P2P loan originator score
The re:think P2P loan originator score rates 100+ loan originators on six balance-sheet criteria: reporting, profitability, return on assets, equity ratio, liquidity and portfolio quality (loan losses). The assessment is based on audited financial statements where available. The P2P platforms themselves are rated separately by the re:think P2P Risk Score.
On many P2P platforms, investors can choose from a variety of different lending companies. In this regard, past experiences have shown repeatedly that quality is often more important than quantity.
So how can one identify the best loan originators?
One of the most important factors to consider is financial stability. Therefore, the loan originators on this page are examined against six separate criteria, with a total score of up to 100 points.
Based on all lending companies with a total score.
How The Lender Comparison Score Works
There are six criteria in total, each rated on a scale from 1 (weakest level) to 5 (strongest level). Every level is multiplied by its own weight. Added up, this produces a total score of up to 100 points. Here is the breakdown:
| Criterion | Weight | Max. Points |
|---|---|---|
| Reporting (Audit Quality) | 4 | 20 |
| Profitability | 2 | 10 |
| Return on Assets (ROA) | 2 | 10 |
| Equity Ratio | 5 | 25 |
| Liquidity | 2 | 10 |
| Portfolio Quality (Loan Losses) | 5 | 25 |
| Total | 20 | 100 |
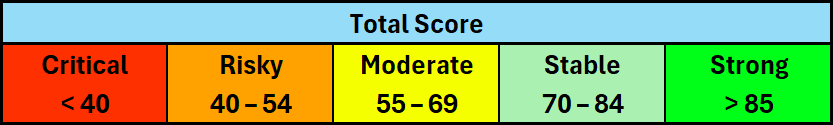
Total Score
The loan originator comparison score condenses all available financial metrics and qualitative information into a single risk indicator. Each level is multiplied by its weight and the results are added up across all six criteria.
How each criterion is calculated and assessed is explained below the tables: → Six Lender Comparison Criteria In Detail
How To Read The Tables
- Sorting: Rated loan originators come first, ordered by total score. Below them are the companies that have financial metrics but no total score. Right at the bottom are the loan originators without a usable report.
- No Total Score: Some holdings and project companies have no loan book of their own. The portfolio criterion does not apply to them, which is why a total score is withdrawn.
- Missing Data: Transparency is a core part of sound financial management. If a loan originator does not disclose a particular metric, this is treated as elevated risk and results in 0 points.
- Year: Links directly to the annual report that was evaluated. Every rating can therefore be verified at the source.
- Footnote (*): Portfolio quality derived from the substitute calculation using the provision coverage ratio.
- Empty Cell: Not disclosed in the financial statements.
Afranga
More information about the platform is available in my Afranga review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Stik Credit (BG) | 2025 | Nexia | EUR 2.3M | 7.1% | 44.1% | 2.45 | 34.2% | 81 |
| Credirect (BG) | 2025 | Unaudited | EUR 3.5M | 52.6% | 91.3% | 11.30 | 51.8% | 64 |
| Lendivo (BG) | 2025 | Nexia | EUR 171K | 4.7% | 13.8% | 1.96 | 57.0% | 57 |
| Lev Credit (BG) | 2025 | Unaudited | EUR 255K | 28.8% | 76.2% | 29.0%* | 54 | |
| Swiss Funds (CZ) | 2025 | Unaudited | EUR 22K | 0.8% | 22.3% | 1.11 | 24.4%* | 38 |
| Tiberus (BG) |
Bondora
More information about the platform is available in my Bondora Go & Grow review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Bondora Group (EE) | 2025 | KPMG | EUR 9.5M | 29.6% | 74.7% | 3.18 |
Debitum
More information about the platform is available in my Debitum review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Sandbox (LV) | 2025 | BK Partneris | EUR 235K | 6.7% | 31.7% | 0.83 | 56 | |
| Evergreen (EE) | 2024 | Unaudited | EUR 279K | 9.2% | 24.7% | 2.08 | 49 | |
| Juno (LV) | 2024 | Unaudited | EUR 158K | 1.4% | 7.6% | 0.10 | 28 | |
| Triple Dragon (GB) | 2024 | Unaudited | EUR 0 | 0.0% | 0.0% | 3.35 | 27 | |
| Baltic Terra (LV) | 2025 | S. Vilcānes audits | EUR 266K | 91.9% | 99.0% | 95.54 | ||
| LFDF (LV) | 2025 | S. Vilcānes audits | EUR 1.6M | 6.5% | 7.9% | 0.08 |
Esketit
More information about the platform is available in my Esketit review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Jet Finance (KZ) | 2024 | Grant Thornton | EUR 1.2M | 4.4% | 20.6% | 1.15 | 13.4% | 79 |
| Spanda Capital (ES) | 2024 | Cortés y Asoc. | EUR 12K | 0.4% | 0.2% | 0.85 | 34.0% | 41 |
| Mojo Capital (AE) | 2025 | Unaudited | EUR 327K | 3.9% | 1.6% | 17.71 | 35 | |
| JMD Investments (LV) | 2024 | Baker Tilly | EUR 4.6M | 32.2% | 51.8% | 0.25 | ||
| A24 Group | ||||||||
| Credus Capital | ||||||||
| MDI Finance | ||||||||
| Nimbura |
Income Marketplace
More information about the platform is available in my Income Marketplace review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| ITF Group (BG) | 2024 | Ecovis | EUR 1.8M | 11.0% | 34.3% | 2.13 | 34.0% | 76 |
| Virtus (XK) | 2025 | BDO | EUR 372K | 3.3% | 11.4% | 0.46 | 2.6% | 75 |
| Autofino (LT) | 2024 | Crowe | EUR 51K | 1.5% | 15.8% | 0.77 | 9.6% | 67 |
| DanaKredi (ID) | 2024 | Unaudited | EUR 14.1M | 26.5% | 68.2% | 3.13 | 59 | |
| Simpleros (ES) | 2024 | Unaudited | EUR 201K | 12.3% | 31.3% | 2.28 | 56.2% | 59 |
| Hoovi (EE) | 2024 | Unaudited | EUR 662K | 9.9% | 12.1% | 0.54 | 12.3% | 58 |
| Ibancar (ES) | 2025 | Unaudited | EUR 730K | 3.4% | 14.6% | 1.0% | 57 | |
| Pinjam Yuk (ID) | 2025 | Unaudited | EUR 10.6M | 21.9% | 57.0% | 64.4% | 52 | |
| Mocasa (PH) | 2025 | Unaudited | EUR (167K) | (7.0%) | 42.8% | 1.50 | 67.8% | 46 |
| Current Auto (LT) | 2023 | Unaudited | EUR (54K) | (0.7%) | (2.9%) | 2.68 | 11.0% | 43 |
| One Leasing (MK) | 2025 | Russell Bedford | EUR (129K) | (11.7%) | (12.5%) | 0.06 | 15.0%* | 32 |
| Sandfield (GB) | 2025 | Unaudited | EUR 2.4M | 8.5% | (0.7%) | 27 | ||
| Current Auto (LV) | 2024 | Unaudited | EUR (913K) | (19.4%) | (55.2%) | 1.08 | 55.2%* | 24 |
| Danabijak (ID) | 2023 | Kreston | EUR 16K | 2.6% | 21.4% | 0.66 |
Lendermarket
More information about the platform is available in my Lendermarket review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Credifiel (MX) | 2024 | RSM | EUR 7.1M | 6.0% | 35.6% | 1.16 | 14.8% | 78 |
| Creditstar Group (EE) | 2025 | KPMG | EUR 13.5M | 3.0% | 15.6% | 0.44 | 14.6% | 73 |
| Rapicredit (CO) | 2024 | Nexia M&A | EUR 457K | 1.6% | 19.9% | 2.04 | 10.4% | 73 |
| Best Credit Invest (RO) | 2025 | 3B Expert Audit | EUR 21K | 3.2% | 39.0% | 23.6%* | 59 | |
| Dineo (ES) | 2024 | BNFIX | EUR 2.4M | 25.0% | 0.7% | 3.36 | 46.3% | 52 |
| Ok Credit (MD) | 2025 | Unaudited | EUR 21K | 4.9% | 24.6% | 6.62 | 47 | |
| Flowpay (CZ) | 2024 | Unaudited | EUR 106K | 5.3% | 4.7% | 29 | ||
| Rapicredit Iberica |
Lendiball
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Victoria Credit (MD) | 2025 | MOLDAUDITING | EUR 39K | 10.3% | 60.0% | 33.3%* | 60 | |
| Virtula Finance (RO) | 2024 | ASTRA | EUR (13K) | (6.7%) | 98.4% | 52.4% | 50 |
Loanch
More information about the platform is available in my Loanch review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Tambadana (MY) | 2024 | SY Lee & Co. | EUR 470K | 15.2% | 2.5% | 2.63 | 38.6% | 54 |
| Ammana (SG) | 2023 | Helmi Talib | EUR (3.7M) | (380.3%) | (522.5%) | 2.36 | 77.1% | 36 |
| AhaPay (MY) | 2025 | SFAI | EUR (824K) | (39.4%) | (16.0%) | 0.86 | 191.6% | 34 |
Mintos
More information about the platform is available in my Mintos review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Eleving Group (LU) | 2025 | BDO | EUR 29.2M | 5.5% | 18.3% | 3.42 | 21.8% | 80 |
| Hipocredit (LT) | 2025 | Nexia | EUR 1.1M | 4.2% | 15.8% | 14.52 | 80 | |
| Gocredit (MX) | 2025 | Unaudited | EUR 4.4M | 10.1% | 44.2% | 7.35 | 13.8% | 79 |
| Credifiel (MX) | 2024 | RSM | EUR 7.1M | 6.0% | 35.6% | 1.16 | 14.8% | 78 |
| Financiera Mexi (MX) | 2024 | BDO | EUR 1.8M | 3.0% | 35.0% | 2.66 | 11.0% | 78 |
| Placet Group (EE) | 2025 | KPMG | EUR 5.6M | 6.3% | 38.4% | 4.76 | 20.3% | 77 |
| IuteCredit (MD) | 2024 | Baker Tilly | EUR 2.4M | 4.1% | 32.9% | 2.74 | 17.5% | 75 |
| Mozipo Group (RO) | 2024 | Unaudited | EUR 178K | 3.3% | 41.6% | 1.92 | 12.5% | 75 |
| Sun Finance Group (LV) | 2025 | BDO | EUR 58.3M | 20.7% | 33.0% | 3.54 | 40.0% | 75 |
| ESTO (EE) | 2024 | Unaudited | EUR 11.3M | 16.9% | 33.4% | 2.71 | 10.6% | 74 |
| Finclusion (KE) | 2025 | PwC | EUR 31K | 0.3% | 29.2% | 13.9% | 74 | |
| Eleving (BW) | 2025 | BDO | EUR 1.3M | 4.6% | 22.4% | 14.9% | 73 | |
| Eleving (GE) | 2025 | Unaudited | EUR 1.7M | 5.6% | 74.9% | 2.22 | 19.5% | 72 |
| IuteCredit (MK) | 2024 | Moore Stephens | EUR 2.0M | 5.4% | 15.4% | 7.41 | 27.5% | 71 |
| Mozipo Group (LT) | 2025 | Grant Thornton | EUR 359K | 2.0% | 29.6% | 20.4%* | 71 | |
| Eleving / Mogo (MD) | 2024 | BDO | EUR 1.3M | 6.9% | 12.3% | 14.4% | 70 | |
| Eleving / Sebo (MD) | 2025 | BDO | EUR 2.6M | 8.7% | 31.2% | 31.0% | 70 | |
| ID Finance (ES) | 2025 | EY | EUR 20.4M | 15.4% | 23.5% | 2.23 | 59.6% | 70 |
| Cash Credit (BG) | 2024 | Einzelprüfer | EUR 265K | 4.0% | 55.4% | 1.80 | 1.7% | 69 |
| DelfinGroup (LV) | 2025 | BDO | EUR 9.6M | 6.6% | 18.5% | 0.45 | 33.1% | 67 |
| Iute Group (EE) | 2025 | KPMG | EUR 9.9M | 2.1% | 15.8% | 24.5% | 66 | |
| Eleving / AS Mogo (LV) | 2024 | BDO | EUR (969K) | (2.6%) | 72.4% | 2.29 | 43.7% | 64 |
| BB Finance (EE) | 2024 | KPMG | EUR 1.1M | 5.0% | 18.0% | 25.8% | 63 | |
| Restock Tech Group (ID) | 2025 | Unaudited | EUR 137K | 1.6% | 17.5% | 6.72 | 8.6% | 63 |
| Eleving (AM) | 2024 | Unaudited | EUR 3.5M | 20.0% | 61.5% | 1.58 | 7.7%* | 62 |
| Eleving (LT) | 2025 | Unaudited | EUR 213K | 0.9% | 16.3% | 2.46 | 5.0% | 61 |
| Pinjam Yuk (SG) | 2025 | Unaudited | EUR 1.5M | 5.2% | 42.8% | 1.73 | 79.0% | 60 |
| ID Finance Gruppe (ES) | 2024 | EY | EUR 6.6M | 4.2% | 16.0% | 61.5% | 58 | |
| Eleving (AL) | 2025 | Unaudited | EUR 6.0M | 14.5% | 30.2% | 23.1% | 57 | |
| Eleving / FINMAK (MK) | 2025 | Unaudited | EUR 4.4M | 17.0% | 53.6% | 30.4% | 57 | |
| MK Kredit (RO) | 2025 | Unaudited | EUR 2.0M | 3.8% | 19.4% | 10.2% | 57 | |
| Watu Credit (UG) | 2024 | Unaudited | EUR 8.3M | 9.1% | 28.9% | 18.7% | 57 | |
| Vivalia (MX) | 2025 | Unaudited | EUR 97K | 0.2% | 46.2% | 15.6% | 56 | |
| Evergreen Finance (GB) | 2025 | Unaudited | EUR 1.7M | 5.2% | 22.4% | 1.59 | 33.6% | 55 |
| IuteCredit (AL) | 2024 | Unaudited | EUR 4.7M | 5.6% | 26.7% | 1.42 | 35.7% | 55 |
| Credius (RO) | 2025 | Unaudited | EUR 1.7M | 7.6% | 40.7% | 35.6% | 52 | |
| Mogo (KZ) | 2025 | Unaudited | EUR 8.1M | 7.2% | 16.3% | 18.4% | 52 | |
| MK Kredit (MD) | 2025 | Unaudited | EUR 241K | 1.0% | 32.7% | 24.7% | 51 | |
| Sun Finance (SE) | 2025 | Einzelprüfer | EUR 2.5M | 9.2% | 9.6% | 1.11 | 65.7% | 49 |
| IDF Eurasia (KZ) | 2024 | Unaudited | EUR 2.6M | 1.2% | 18.7% | 1.37 | 39.4% | 46 |
| Monefit (EE) | 2025 | Unaudited | EUR 88K | 0.1% | 10.2% | 7.3% | 46 | |
| Eleving (EE) | 2025 | Unaudited | EUR 16K | 0.0% | 7.6% | 0.99 | 20.9% | 45 |
| Creditstar (FI) | 2025 | Unaudited | EUR 96K | 0.1% | 2.9% | 10.5% | 41 | |
| IuteCredit (BG) | 2024 | AELB Bulgaria | EUR (1.2M) | (8.1%) | 8.3% | 1.21 | 57.8% | 41 |
| Hipocredit (LV) | 2025 | Unaudited | EUR 206K | 1.2% | 14.6% | 8.12 | 38 | |
| Eleving / mogo (LT) | 2024 | ROSK | EUR (667K) | (2.6%) | 7.8% | 32 | ||
| ESTO (LT) | 2024 | Tezaurus | EUR (1.1M) | (19.9%) | (57.7%) | 43.7% | 26 |
Monefit SmartSaver
More information about the platform is available in my Monefit SmartSaver review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Creditstar Group (EE) | 2025 | KPMG | EUR 13.5M | 3.0% | 15.6% | 0.44 | 14.6% | 73 |
Nectaro
More information about the platform is available in my Nectaro review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| CreditPrime (RO) | 2025 | Forvis Mazars | EUR 3.6M | 26.1% | 41.9% | 3.34 | 18.1% | 90 |
| CreditPrime (MD) | 2025 | Crowe | EUR 657K | 5.3% | 15.9% | 0.57 | 28.0% | 57 |
| Abele Finance (LV) | 2025 | Review only | EUR (114K) | (1.6%) | 3.3% | 0.90 |
PeerBerry
More information about the platform is available in my PeerBerry review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| PujckaPlus (CZ) | 2025 | SolveBros | EUR 1.7M | 19.9% | 53.3% | 2.06 | 28.0% | 77 |
| OneCredit (KZ) | 2025 | Almir | EUR 666K | 11.2% | 51.2% | 3.37 | 145.8% | 76 |
| ACredit (RO) | 2025 | Savvy Audit | EUR 2.6M | 69.6% | 43.3% | 25.4% | 69 | |
| FinWind (LT) | 2025 | AUDIFINA | EUR 1.9M | 73.7% | 83.2% | 4.98 | 67 | |
| Smartcredito (ES) | 2025 | Unaudited | EUR 523K | 6.7% | 21.7% | 13.22 | 6.8% | 67 |
| NovaLend (PL) | 2025 | Quantum Audyt | EUR 38K | 0.6% | 8.9% | 0.91 | 6.0% | 58 |
| A-Credit (KZ) | 2025 | Baker Tilly | EUR (306K) | (2.0%) | 72.5% | 1.81 | 57.0% | 52 |
| Findom (KZ) | 2025 | Baker Tilly | EUR (1.1M) | (44.4%) | 23.4% | 1.04 | 203.6% | 52 |
| Credito365 (MX) | 2025 | Servicios Vanguardistas | EUR 1.4M | 26.5% | (10.0%) | 8.06 | 45 | |
| Credit365 (MD) | 2025 | Manager Audit | EUR 91K | 0.7% | 14.8% | 4.45 | 44 | |
| CashX (NG) | 2025 | BSG Professional | EUR (26K) | (3.1%) | (7.0%) | 457.62 | 40.1% | 40 |
| LendPlus (KE) | 2025 | MGK | EUR (26K) | (0.5%) | (6.5%) | 19.02 | 49.0% | 38 |
| Credito365 (CO) | 2025 | Revisor Fiscal | EUR (304K) | (22.2%) | (17.3%) | 2.34 | 70.8% | 36 |
| LendPlus (ZA) | 2025 | Mahleka D | EUR (6.2M) | (119.8%) | (110.1%) | 1.81 | 107.4% | 34 |
| Cash-Express (PH) | 2025 | Unaudited | EUR (732K) | (36.3%) | (185.2%) | 4.35 | 50.4% | 28 |
| Lendi (AR) | 2025 | J. C. Pisaco | EUR (116K) | (54.7%) | (44.7%) | 0.66 | 19 | |
| Mira Prima (ES) | 2025 | Unaudited | EUR (135K) | (6.4%) | (6.3%) | 0.79 | 17 | |
| Mira Segundo (ES) | 2025 | Unaudited | EUR (282K) | (5.6%) | (5.5%) | 0.06 | 15 | |
| Aventus Biznes (PL) | ||||||||
| Credit365 (AU) | ||||||||
| Jabulani Money (ZA) | ||||||||
| PaydayLoanPlus (CA) | ||||||||
| Prestamo365 (PE) | ||||||||
| PrimeLoans (ZA) | ||||||||
| RealCredito (ES) | ||||||||
| TuParcero (CO) |
Robocash
More information about the platform is available in my Robocash review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| UnaFinancial (SG) | 2024 | Unaudited | EUR 553K | 0.5% | 3.8% | 51.8% | 22 |
Swaper
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Wandoo Finance Group (LV) | 2025 | Dzerele | EUR 3.7M | 7.3% | 18.0% | 2.50 | 52.7% | 62 |
| SW Finance (EE) | 2024 | Assertum | EUR (30K) | (0.3%) | (0.3%) | 1.23 | 27 |
Twino
More information about the platform is available in my TWINO review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| Fincard (PL) | 2025 | BDO | EUR 10.4M | 18.5% | 42.5% | 1.81 | 37.1% | 66 |
Viainvest
More information about the platform is available in my Viainvest review.
| Lender | Year | Audited | Profit | ROA | Equity | Liquidity | Losses | Score |
|---|---|---|---|---|---|---|---|---|
| VIA SMS (LV) | 2025 | BDO | EUR 2.6M | 4.8% | 13.7% | 1.00 | 4.9% | 77 |
| VIA SMS (CZ) | 2025 | Unaudited | EUR (12K) | (0.3%) | 19.7% | 1.13 | 2.4% | 54 |
| Viaconto (SE) | 2025 | Unaudited | EUR 2.4M | 11.0% | 15.1% | 1.13 | 38.6% | 50 |
| Viaconto Minicredit (RO) | 2025 | Unaudited | EUR (255K) | (21.6%) | 42.9% | 82.0%* | 40 |
Six Lender Comparison Criteria In Detail
Below is an overview of the criteria applied when assessing financial stability, including what each one means, how it is calculated and how to interpret it.
Reporting Standard
Scale:
- Level 5 (strong): Audited under IFRS by a top-10 firm
- Level 4 (stable): Audited under IFRS by a smaller audit firm
- Level 3 (medium): Audited under local GAAP by a reliable auditor
- Level 2 (risk): The auditor is not an identifiable firm, the opinion is qualified, or it is only a review engagement
- Level 1 (critical): No audit, management accounts only or unaudited figures
The top 10 are: Deloitte, PwC, EY, KPMG, BDO, RSM, Grant Thornton, Forvis Mazars, Baker Tilly and Crowe.
Comments by the auditor on the state of the business do not feed into this criterion, for instance a going-concern uncertainty or an “emphasis of matter”. These relate to the economic situation, which is already measured through equity, profit, liquidity and loan losses. Penalising it twice is deliberately avoided. A qualified opinion, on the other hand, automatically means level 2, because it calls the reliability of the figures themselves into question.
Profitability
Scale:
- Level 5 (strong): Profits in both of the last two years
- Level 4 (stable): Turnaround – profit following a loss-making year
- Level 3 (medium): Break-even (within ±1% of total assets) following a profitable year
- Level 2 (risk): Loss following a profitable year
- Level 1 (critical): Losses in both of the last two years
Where no prior-year result is available, the criterion is capped at level 4 (at level 1 in the case of a loss).
Return on Assets
Scale:
- Level 5 (strong): above 5%
- Level 4 (stable): 3% to 5%
- Level 3 (medium): 1% to 3%
- Level 2 (risk): 0% to 1%
- Level 1 (critical): negative
Equity Ratio
Scale:
- Level 5 (strong): 40% and above
- Level 4 (stable): 25% to 40%
- Level 3 (medium): 15% to 25%
- Level 2 (risk): 5% to 15%
- Level 1 (critical): below 5%
Liquidity
Scale:
- Level 5 (strong): above 2.0
- Level 4 (stable): 1.5 to 2.0
- Level 3 (medium): 1.0 to 1.5
- Level 2 (risk): 0.5 to 1.0
- Level 1 (critical): below 0.5
- Level 0 (not disclosed): cannot be calculated
Portfolio Quality
Scale:
- Level 5 (strong): below 5%
- Level 4 (stable): 5% to 15%
- Level 3 (medium): 15% to 25%
- Level 2 (risk): 25% to 35%
- Level 1 (critical): above 35%
- Level 0 (not disclosed): no usable information on loan losses
The denominator is income from the lending business, meaning interest plus the fees paid by the borrower. It excludes brokerage and agency commissions earned on behalf of third parties, income from securities and intra-group interest. The numerator, on the other hand, includes losses from the sale of non-performing receivables. The reasoning: Selling a defaulted portfolio at a discount instead of writing it off still realises the loss.
Substitute calculation: Where the financial statements show no impairment charge for the year but only the accumulated allowance, the provision coverage ratio is used instead (accumulated allowance ÷ gross portfolio). These rows are marked with an asterisk (*). The levels for this are: below 3% / 3–6% / 6–10% / 10–15% / above 15%.
Disclaimer
The published financial results were evaluated to the best of my knowledge and belief. Individual errors can nevertheless not be ruled out. Every year figure in the tables therefore links to the original source. Investors should engage with the figures presented here independently and responsibly. Viewed in isolation, financial metrics are not a measure of a loan originator’s success or failure. Factors such as country risk, guarantees, buyback obligations and group liability have to be taken into account alongside them.
I’m Denny Neidhardt, the founder of re:think P2P. On this blog, I help retail investors make smarter, well-informed investment decisions in the world of P2P lending. Since 2019, I’ve been publishing in-depth analyses, platform reviews, and risk assessments to bring more transparency to this investment space. My goal is to challenge marketing claims, question developments, and empower investors with honest, independent insights.
Hi Denny,
Thank you for the great work.
I wanted to suggest a small modification to make the report even more intuitive: what do you think about adding an extra column for the previous score? A simple column with the previous number would suffice. This way, it would be much easier to see the evolution and trend of the data compared to the previous analysis.
Hi Danny, I find your page very insightful. One suggestion: would it be possible to include a column indicating the date of analysis for each lender? I’ve noticed that some data remains unchanged despite more recent updates from the providers themselves.
Hi Itta,
no, I don’t plan to add a column for the date of the analysis.
Kindly indicate which annual reports have recently been published.
Please note that I don’t cover interim reports.
Hi Denny. The Impairment ratio of Stik Credit now is 22%? Why have you lower it if no new audited report?
Thanks in advance
I was reviewing the numbers again prior my visit to Sofia. Turns out I made a mistake the first time. Now it displays the correct impairment ratio.
Thanks for Great data!
Would there be interest in reviewing PeerBerry’s Aventus Group as a whole? Or for example the iuvo Group and from that also MGF? And why not Bondster?
Thanks a lot for creating this useful comparison. It definitely took a lot of time, and we highly appreciate it.
Thank you so much for your work, I’m really glad I found this page ????????????! Hive5’s loan originators would be a great addition to your analysis.
Hi Anna,
thanks for sharing your feedback. Let’s see. I think the review is already enough exposure for them on my blog.
Best, Denny
Hi Denny,
First, I just want to say thank you for the excellent and detailed analysis you provide on Rethink P2P.
I have a quick question about your scoring methodology. I noticed that you don’t seem to assign a specific score to the “age” or operational history of the companies.
I was just wondering about the reasoning for this. For example, in the current rating, a company with good financials that has been active for less than 5 years seems to have no scoring difference compared to a company at a similar level that has been active for 20 years.
Was this a conscious decision? I’d be interested to know your thoughts on why longevity isn’t factored in as a specific scoring point.
Thanks again for your great work!
Hi Itta,
thanks for your feedback on the lender comparison page. The track record is indeed an important aspect of the overall lender assessment. However, this comparison focuses solely on financial stability, which is why I am looking only at the most recent financial data.
Including past financial performance could potentially penalize younger, yet stable, lending companies. At the same time, how would someone assess if an established loan originator has done good or bad in the past? Does a low rating become better, despite having great financials in the past?
Having the overall picture in mind is important. But for evaluating financial stability, only recent results provide the most relevant and comparable benchmark for all lenders.
Thanks again for sharing your feedback!
Denny
Comparison of originators is one of the most valuables things! I may suggest update it on regular basis and add new (if possible). Thank you.
Hi Mindaugas,
for now, updates will happen on a monthly basis.
Are there any bigger lenders that are currently missing?
Regards,
Denny
Hi Denny, I suggest to analyse:
Estateguru
Iuvo
LandSecured
Bondster
Peerbery
Robocash
Lendermarket
Esketit
Paskolu Klubas
Reinvest24
HeavyFinance
Indemo
Crowdpear
Fintown
Swaper
Twino
Afranga, StikCredit
Moncera
Bulkestate
Nordstreet
Crowdestate
Profitus
Inrento
Viainvest
Nectaro
Scramble
Stockcrowdin
Civislend Platforms and originators (where not analysed). I personally use ChatGPT plus in this case. I found Eleving group is missed. All the best, Mindaugas
Doesn’t anyone notice that you copy everything P2P Empire does? It was really noticeable recently. Even your portfolio is almost identical.
P2P Empire publishes lender reviews -> Danny publishes lender reviews.
P2P Empire invests in Afranga -> Denny invests in Afranga.
and so on…
It would be cool if you created your own content again 🙂 The blog is just a shadow of what it used to be. Very sad development….
Thanks for your feedback. Let me clarify a few things: I have a lot of respect for P2P Empire. They are doing a great job. As far as I know, I invested in Afranga before they did. The same goes for Nectaro, by the way. As for the lender page, I started publishing lender analyses earlier this year as part of my platform reviews (e.g., Income Marketplace, Nectaro). What has changed is that I’m now expanding this format and consolidating the information on one page to make it more structured and accessible for readers. In addition, we use different KPIs to assess financial performance. So while there may be some overlapses and similarities, I don’t believe your accusations are justified.
Have a good day,
Denny
Hi Denny,
What an impressive dashboard.
I never took the time to build mine / the size of my portfolio doesn’t justify so much work.
It would be great if you could extend it to other platforms.
The maintenance will be a real challenge I guess.
Thanks a lot.
Patrick,
Hi Patrick,
thanks for your feedback.
Mintos and PeerBerry will be added in the next days as well.
Indeed, maintenance is going to be a challenge. Maybe I will perform an update once each quarter.
So long,
Denny