
 Posted by
The portfolio update has been a regular format on my blog since January 2019. On a monthly basis, investors get an honest and transparent look at the latest developments in my personal P2P lending portfolio, including income, performance, transactions, and portfolio value.
I also cover changes and developments at various platforms within the P2P market. Anyone who wants to look more closely into individual platforms will find detailed analyses on my P2P platform reviews page. Current cashback promotions and bonus offers are summarized on my bonus page.
For up-to-date information, I recommend following my news page. There, I share timely reactions, evaluations, and assessments as soon as new developments occur. Alternatively, you can also subscribe to my Telegram group or my WhatsApp channel (both free of charge).
P2P Portfolio Update: November 2026
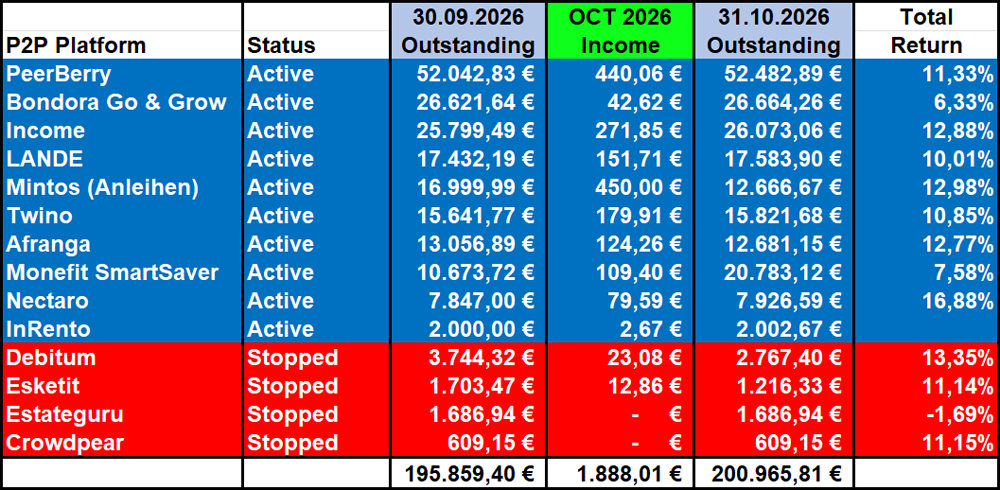
Here is the current state of my personal P2P lending portfolio as of the end of October 2026.
Income
In October 2026, I generated €1,888 in income from my outstanding P2P lending portfolio. This is the third-highest figure of the current calendar year, around €200 above the yearly average (€1,687).
New personal income records at individual P2P platforms were achieved last month on TWINO with €180 and on LANDE with €152.
Performance
The best overall performance in my P2P portfolio currently comes from Nectaro at 16.9%. The reason for the above-average return is my active investment approach, which is focused on taking advantage of the various bonus campaigns. In second place is Debitum at 13.4%, followed by Mintos (bonds) at 13% and Income Marketplace at 12.9%.
At the other end of my performance table, Estateguru remains the negative leader with a return of -1.7%.
Transactions
Last month, there were a total of five new transactions in my P2P portfolio.
Deposits: EUR 10,000
- Monefit SmartSaver: I transferred €10,000 to my main account at Monefit SmartSaver. My focus on the platform remains on providing liquidity, which I have already taken advantage of several times this year.
Withdrawals: EUR 6,868.25
- Mintos: At Mintos, last month was quite transaction-heavy, ending with €4,868.25 in withdrawals. The largest item was the Mintos bond itself, which I sold early at face value on the secondary market. The final coupon payment of €120 also came in and was subsequently withdrawn. In addition, my IuteCredit bond reached maturity, with principal and coupon payments of €6,330 providing a welcome windfall in the account. My search for new bond investments was successful as well: I invested €6,000 in ID Finance, maturing in less than two years. The remaining €418.25 relate to a repayment from Credifiel.
- Debitum: At Debitum, I was able to withdraw another €1,000, further accelerating my exit from the platform. Seven months after my updated LFDF article, there are still no efforts to push for an independent review of the LFDF transaction prices. My leap of faith that Debitum has honest intentions and would seriously address the issue is now completely used up. Since the majority of investors continue to invest diligently, I am not worried about my repayments at the moment. However, conservative investors should be aware that repayment from ongoing operations could become difficult at some point in the future.
- Esketit: At Esketit, there was another opportunity to withdraw repaid funds. In October, a further €500 flowed out of the account.
- Afranga: Here, €500 was withdrawn as well, to bring my Stikcredit position more in line with its risk profile.
Overall, the net deposit and withdrawal balance was positive €3,131.75 last month. For 2026 as a whole, €4,937 more has still been withdrawn than deposited.
P2P Portfolio
The value of my outstanding P2P lending portfolio increased from €195,859 to €200,966 in October 2026. The liquidity-focused portion of my P2P portfolio, consisting of Bondora Go & Grow and Monefit SmartSaver, amounted to €47,447 (23.6%).
P2P Lending News: October 2026
Below is a summary of the most important news and developments in the P2P lending market.
PeerBerry has entered its tenth year of business. Since its launch in 2017, around €3.6 billion in loans have been financed and more than €60 million in interest paid out to investors. The managed portfolio has grown by 38% since the beginning of the year to €160.9 million.
Income Marketplace has introduced an inactivity fee. There were also three updates on the lender side: Hoovi submitted an IFRS-audited annual report for the first time, improving its lender score from 58 to 71 points, Autofino loses five points following its audited 2025 figures, and Danabijak slipped into the red in 2025.
TWINO has communicated a cyberattack which, according to the platform, affected around 8% of investors. In addition, the FLEXI limit was raised to €100,000. Regarding the ongoing UOKiK proceedings against lender Fincard, I published a detailed article, including TWINO’s written answers to my questionnaire.
Mintos has launched stock trading as a new product on the platform. According to the platform, more than 4,000 stocks are available, tradable from €1 via fractional shares, with no order, custody, or withdrawal fees. Limit orders are still in development, so for now only market orders are available.
Lendermarket has introduced two new lenders with Aiffin and Simpleros. Aiffin finances vehicle leasing for micro-enterprises and self-employed workers in France and offers 11 to 15% interest, but has not yet published any financial figures. Spanish lender Simpleros issues short-term consumer loans at 9 to 13% interest and may already be familiar to investors from Income Marketplace, where the lender has been active since August 2025.
Esketit has added Lionpro, a new lender from Latvia. The company finances working capital for the commodity trading business of the group behind it, at 8% interest, secured by a group guarantee and a pledge on trading assets.
Estateguru has now kept its secondary market closed for more than three months. According to the latest information, a reopening is not expected before January 2027 at the earliest. Investors are thus left without the only early exit option from a portfolio of which around 60% is in recovery.
LANDE has published its performance report for September. €2.06 million was financed across 58 projects, at an average interest rate of 11.76%. In Latvia, a state of emergency was declared in the agricultural sector due to persistent rainfall, making it easier for borrowers to defer their repayments in the coming months.
InRento reports a record third quarter with €23.49 million in financed projects, up 76% year-on-year. At the same time, the platform is dealing with two problem cases in Poland: at the Warsaw project Harfowa 10, the loan was terminated after the property sale fell through, while formal debt collection has been underway at the J48 project in Łódź since the beginning of October.
Crowdpear has appointed Donatas Mickus as its new CEO, effective November 3. He previously spent roughly a decade in traditional banking, mostly working in business development. He was recruited by PeerBerry CEO Arūnas Lekavičius.
Indemo considers the risk from the new Spanish housing decrees to be low for its own business model. Among other things, the yet-to-be-passed decrees stipulate that residential properties may not be purchased below 70% of their value, which, according to the platform’s reading, only applies when the creditor takes over the property and not when the claim is purchased.
Modena plans to apply for a MiFID II license. The complete application to the Estonian financial supervisory authority is expected to be submitted around the end of the year. After that, the platform expects a review period of around six months before potentially obtaining the license in the summer of 2027.
Triple Dragon has shared its Q2 Update 2026 with the platform’s most important developments. It reports a quarterly profit of around €178,000, of which almost half is attributable to unrealized currency gains. Equity remains at just 1.2% of total assets, at around €216,000.
New Content from re:think P2P
The following content has been published on the blog and the YouTube channel in recent weeks (videos in German, with English subtitles).
Blog
- P2P Risk Score Update Q3/2026
- P2P Lending Update: October 2026
- €5.3 Million Fine for TWINO Lender? (UOKiK vs. Fincard Explained)
YouTube
- P2P Platform Comparison (Risk Score Q3 2026)
- New #1 in My Portfolio | McDonald’s instead of Go & Grow | P2P Portfolio Update October 2026
- TWINO Under Pressure: Authority Investigates 96% of the Portfolio
- My Income Lenders: 26K and 54% Concentration Risk
I’m Denny Neidhardt, the founder of re:think P2P. On this blog, I help retail investors make smarter, well-informed investment decisions in the world of P2P lending. Since 2019, I’ve been publishing in-depth analyses, platform reviews, and risk assessments to bring more transparency to this investment space. My goal is to challenge marketing claims, question developments, and empower investors with honest, independent insights.