
 Posted by
The portfolio update has been a regular format on my blog since January 2019. On a monthly basis, investors get an honest and transparent look at the latest developments in my personal P2P lending portfolio, including income, performance, transactions, and portfolio value.
I also cover changes and developments at various platforms within the P2P market. Anyone who wants to look more closely into individual platforms will find detailed analyses in my P2P platform review page. Current cashback promotions and bonus offers are summarized on my bonus page.
For up-to-date information, I recommend following my news page. There, I share timely reactions, evaluations, and assessments as soon as new developments occur. Alternatively, you can also subscribe to my telegram group or my whatsapp channel (both free of charge).
P2P Portfolio Update: September 2026
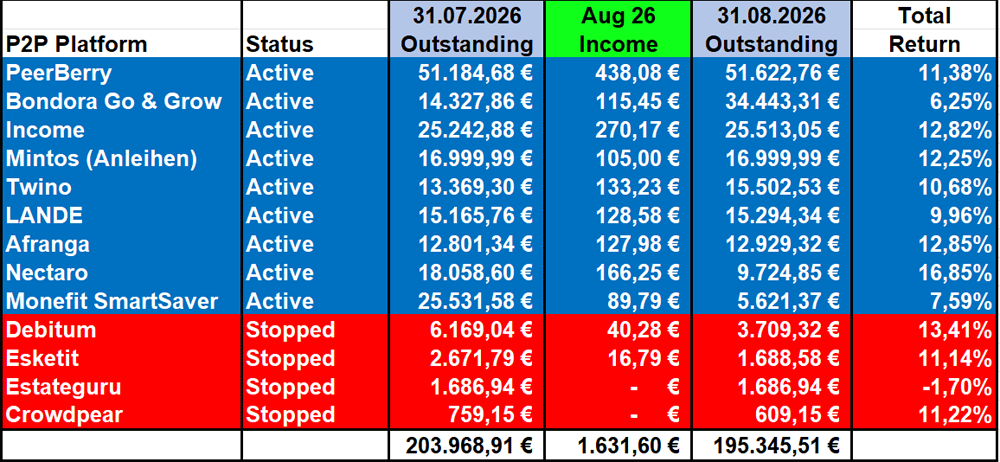
Here is the current state of my personal P2P lending portfolio as of the end of August 2026.
Income
In August 2026, I generated €1,632 in income from my outstanding P2P lending portfolio. This makes it the fifth-highest monthly income of the current calendar year. New personal income records at individual P2P platforms have been achieved on LANDE with €129 and on Afranga with €128.
Performance
The best overall performance in my P2P portfolio currently comes from Nectaro at 16.9%. The reason for the above-average return is my more active investment approach, which is focused on taking advantage of the various bonus campaigns. In second place is Debitum at 13.4%, followed by Afranga at 12.9% and Income Marketplace at 12.8%.
At the other end of my performance table, Estateguru remains the negative leader with a return of -1.7%.
Transactions
Last month, there were a total of eight new transactions in my P2P portfolio.
Deposits: EUR 22,000
- Bondora Go & Grow: I increased my liquidity-focused position in Bondora Go & Grow by another €20,000 last month.
- TWINO: I made another €2,000 deposit into TWINO. The money was invested in 12-month ABS from Poland paying 12% interest.
Withdrawals: EUR 32,255
- Monefit SmartSaver: €20,000 was withdrawn from Monefit SmartSaver. The money was essentially transferred to Bondora Go & Grow via an indirect route.
- Nectaro: At Nectaro, there were more repayments than usual, allowing me to withdraw €8,500 from the platform. I am now considering scaling back my active investment approach. This would mean less effort on my part, but also a slightly lower return.
- Debitum: I was able to withdraw another €2,000 from Debitum, further accelerating my exit from the platform. Five months after my updated LFDF article, there is still plenty of hot air and excuses as to why an independent review of LFDF transaction prices cannot be pursued. My benefit of the doubt that Debitum has genuine intentions and will seriously address the issue has now been completely exhausted. Since the majority of investors continue to invest actively, I am currently not worried about receiving my remaining funds. However, conservative investors should be aware that repayments from ongoing business operations could eventually become difficult.
- Esketit: There was another opportunity to withdraw repaid funds from Esketit. As a result, I withdrew another €1,000 from the platform in August.
- Crowdpear: Same story with Crowdpear, although the amount was only €150.
- Mintos: My Esto bond at Mintos, which still pays 10.5%, has now been in my portfolio for three years. In August, I once again received the scheduled quarterly payment of €105, which I withdrew toward the end of the month.
Overall, the net deposit and withdrawal balance was negative €10,255 last month. For 2026 as a whole, this means that €7,069 more has been withdrawn than deposited. This is a trend I would like to reverse again before the end of the year. I will probably explain in more detail how exactly I plan to achieve this in my next portfolio update.
P2P Portfolio
The value of my outstanding P2P lending portfolio decreased from €203,967 to €195,346 in August 2026. What I actually wanted to avoid has happened, and I am once again below the €200K threshold.
The liquidity-focused portion of my P2P portfolio, consisting of Bondora Go & Grow and Monefit SmartSaver, amounted to €40,065 (20.5%).
I’m Denny Neidhardt, the founder of re:think P2P. On this blog, I help retail investors make smarter, well-informed investment decisions in the world of P2P lending. Since 2019, I’ve been publishing in-depth analyses, platform reviews, and risk assessments to bring more transparency to this investment space. My goal is to challenge marketing claims, question developments, and empower investors with honest, independent insights.